Business Loan With 700+ Credit and $250K Revenue: Which Funding Options Should You Compare?
A business owner with strong credit, several years of operating history and more than $250,000 in annual revenue is in a very different funding position from a startup or a company with inconsistent cash flow.
That stronger profile does not guarantee approval, but it can make multiple financing categories worth comparing rather than accepting the first available offer.
If your company has an active funding need and approximately 700+ credit, two or more years in business and $250,000+ annual revenue, complete the EIN Business Funding Quick Lead Pre-Qualification with the amount needed and specific use of funds.
Why This Profile Can Be More Competitive
The EIN Business Funding guidance describes a generally competitive borrower profile as approximately 700+ personal credit, two or more years in business, $250,000+ annual revenue and positive, consistent cash flow.
It also highlights organized financial statements, tax returns, an established business bank account and a legal business entity.
Meeting those benchmarks does not guarantee approval, but it may give the business more financing categories to compare.
Option 1: Traditional Business Line of Credit
A traditional line of credit may be relevant when the business wants revolving access to capital for recurring needs such as inventory, payroll timing, supplier payments or seasonal expenses.
Common traditional line-of-credit benchmarks in the EIN Business Funding guidance include approximately 720+ personal credit, one to two years in business, $100,000 to $250,000+ annual revenue and positive cash flow.
Banks can also evaluate debt-service coverage, existing debt, industry risk and cash-flow consistency.
Option 2: Business Term Loan
A term loan may fit a clearly defined one-time business expense such as expansion, renovations, technology investment or another significant project.
Common term-loan benchmarks are generally lower than the competitive profile described above: approximately 600 to 680+ personal credit, one or more years in business, $100,000+ annual revenue and positive cash flow.
A stronger borrower may therefore have more ability to compare terms and structures rather than simply focusing on basic eligibility.
Option 3: SBA 7(a) Financing
SBA 7(a) financing may be worth evaluating for qualifying business purposes where the company and borrower meet applicable program and lender requirements.
Repayment ability, business eligibility, ownership, credit and the specific use of proceeds can all matter.
SBA-related financing can involve more documentation and a different process from many online business loans, so the best option depends partly on how quickly the capital is needed.
Option 4: Equipment Financing
If the capital is primarily for machinery, vehicles or another identifiable business asset, equipment financing may be more appropriate than using a general working-capital product.
Matching the financing to the asset can also make the request more specific: the provider can evaluate what is being purchased, the cost and how the equipment supports the business.
Option 5: Online or Alternative Financing
Alternative financing can still be relevant to a strong borrower, especially when speed or documentation requirements matter.
But a company with a competitive profile should compare the total cost and repayment structure rather than accepting higher-cost capital simply because approval may be faster.
Strong Credit Does Not Replace Cash Flow
A 700+ credit score can strengthen the profile, but a business loan ultimately creates another repayment obligation.
If the company already has substantial debt or cash flow has recently weakened, a lender may still limit the amount or structure available.
Why $250K Revenue Is Not the Whole Story
Two companies can each generate $250,000 in annual revenue and have very different financing capacity.
One may produce strong positive cash flow with little existing debt. The other may operate on thin margins while carrying several existing loans.
Revenue should therefore be reviewed alongside cash flow and current obligations.
What Existing Debt Should Be Prepared?
List all open business credit cards, business lines of credit and loans. Include the lender or card name, applicable limit, current balance and open date.
This can help show how much repayment capacity is already committed.
Start With the Use of Funds
The correct financing category depends heavily on why the company needs capital.
- Recurring working capital may point toward a line of credit
- A defined expansion may fit term financing
- Machinery or vehicles may fit equipment financing
- A qualifying acquisition or broader business purpose may justify evaluating SBA financing
Compare Financing—Do Not Shop Only for Approval
A stronger borrower should look beyond whether financing is available. Compare total financing cost, repayment frequency, term, collateral requirements where applicable, personal-guarantee requirements and the impact on future borrowing capacity.
The best funding option is the one that fits the actual business purpose and can be supported comfortably by cash flow.
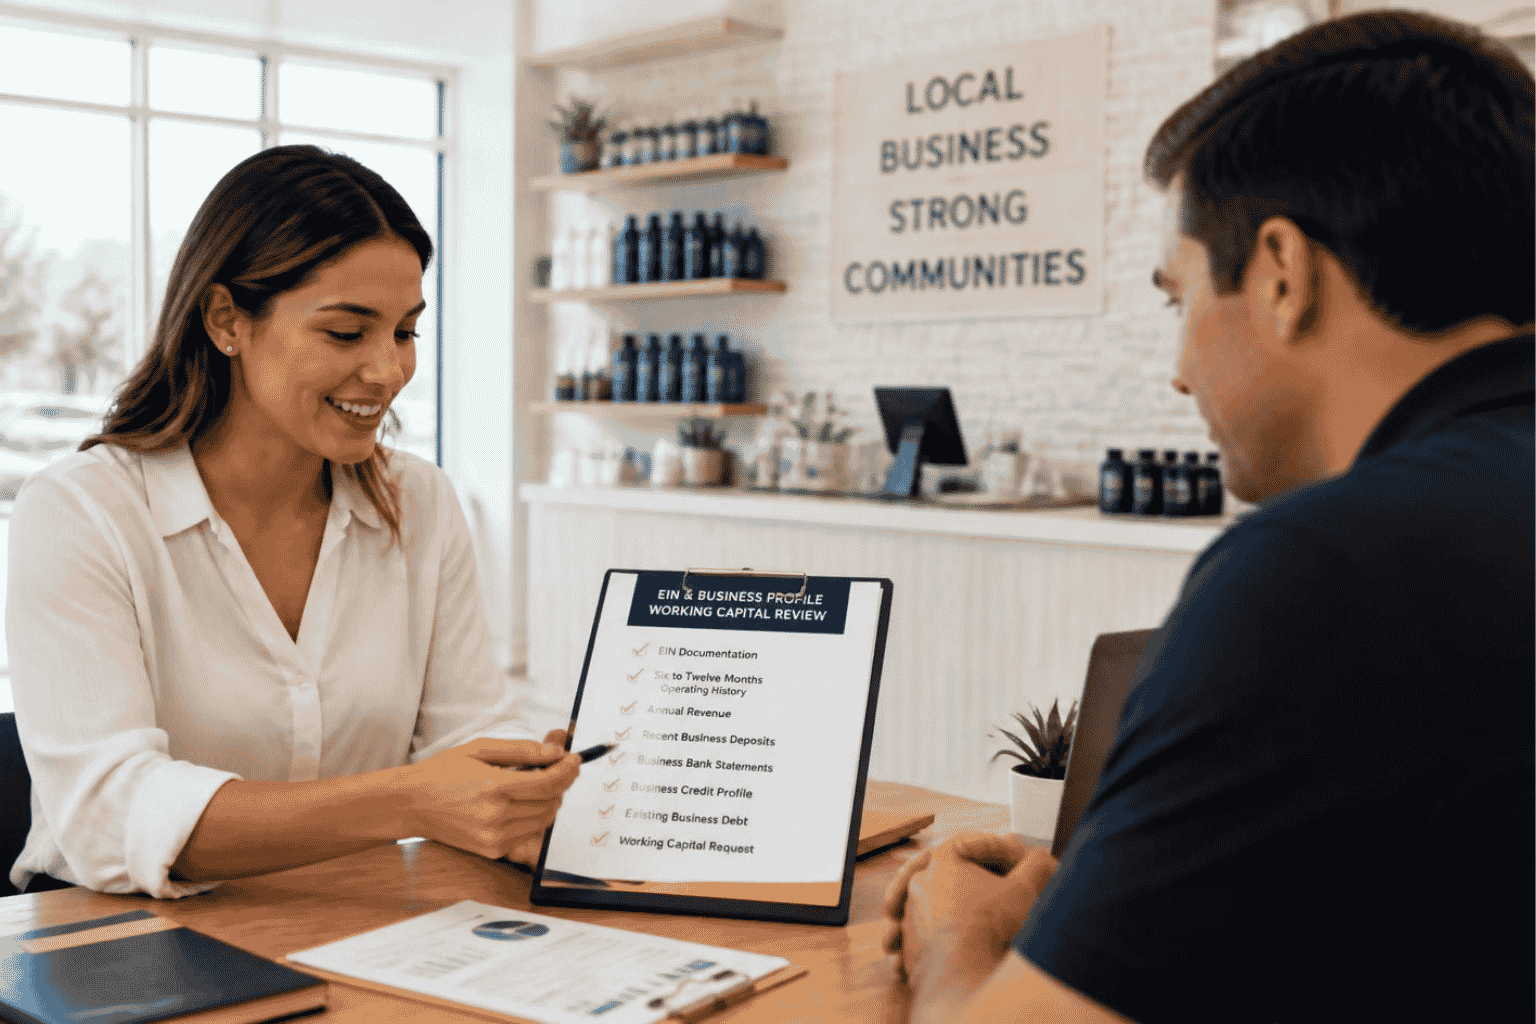
What Should a Strong Borrower Have Ready?
- Requested financing amount
- Exact use of funds
- Current credit score
- Business formation date
- Annual revenue
- Recent business bank activity
- Current financial statements
- Existing business debt
- Ownership information
FAQs
Is 700+ credit and $250K revenue a strong business-funding profile?
It can be competitive when combined with two or more years in business, positive cash flow, organized financials and manageable existing debt.
Which financing options may be worth comparing?
Depending on the use of funds and complete profile, a business may evaluate term loans, lines of credit, SBA financing, equipment financing and other appropriate products.
Does strong credit guarantee a business loan?
No. Providers can still evaluate revenue, cash flow, existing debt, industry, business history and the specific financing request.
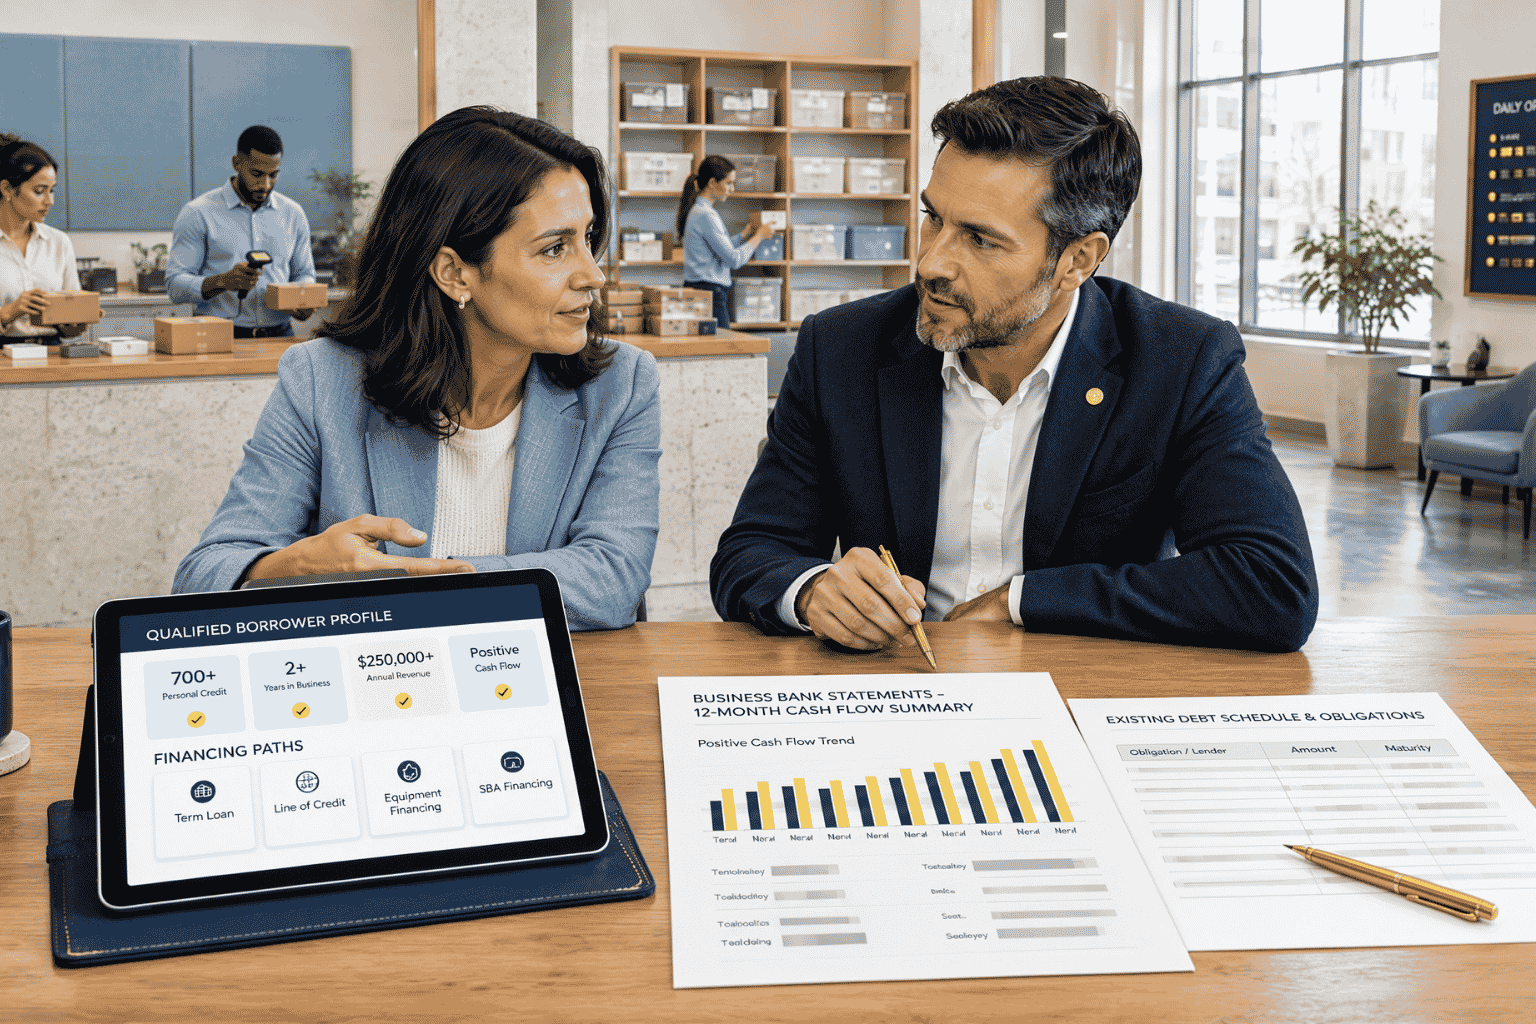 A stronger borrower profile can create more financing options to compare, but cash flow and existing debt still matter.