October 2026 SBA Loan Update: SOP 50 10 8.1 Is Now in Effect—What Borrowers Should Do Before Applying
Business owners preparing for SBA-backed financing in late 2026 should make sure they are working from current requirements rather than relying on a checklist or transaction completed under an older version of SBA lending procedures.
The U.S. Small Business Administration lists SOP 50 10 Version 8.1 with technical updates as effective October 1, 2026. SOP 50 10 governs loan-origination policies and procedures for SBA’s 7(a) and 504 programs.
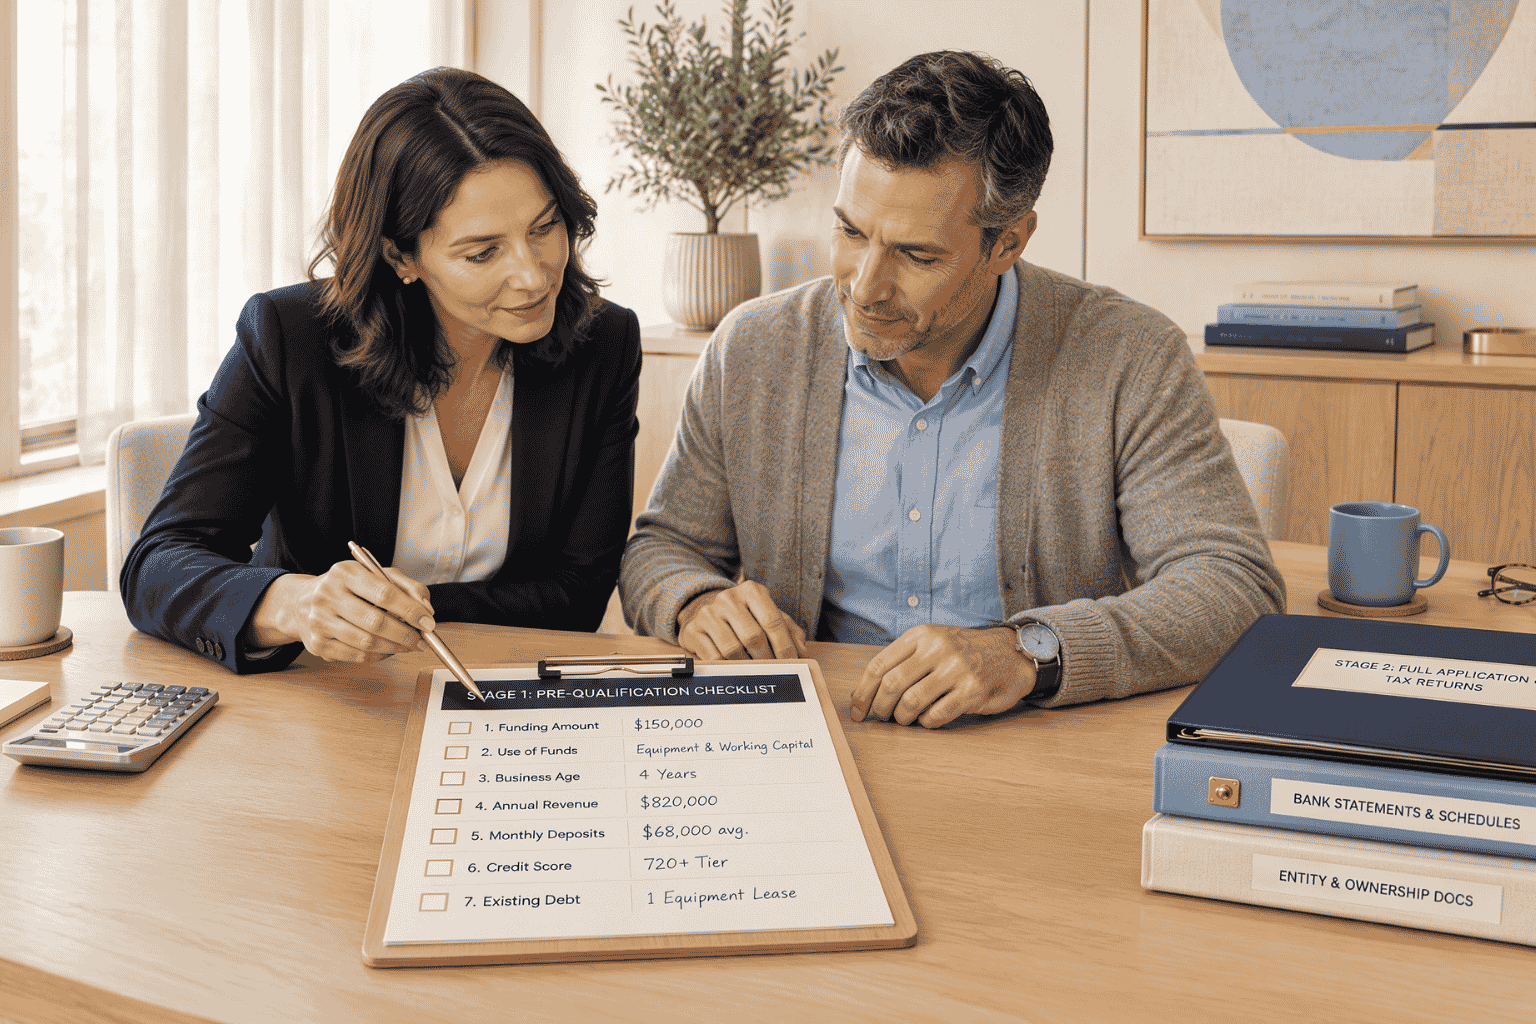
If your company has an active SBA-related funding need, complete the EIN Business Funding Quick Lead Pre-Qualification using your current business information and exact use of funds.
What Changed on October 1, 2026?
SBA’s current document library identifies SOP 50 10 8.1 as the effective version beginning October 1, 2026 and describes the release as containing technical updates.
For borrowers, the practical point is straightforward: lenders processing new SBA 7(a) and 504 requests are operating under the current SBA procedures, so older online checklists may not reflect every current requirement.
Does the SBA Lend the Money Directly?
No. For 7(a) financing, borrowers apply through participating lenders. SBA provides the program framework and guarantee, while the lender works with the borrower on the actual application and determines the documents required for the specific transaction.
What Are the Current High-Level 7(a) Eligibility Principles?
SBA currently states that a business seeking 7(a) assistance generally must be an operating business, operate for profit, be located in the United States, meet applicable SBA size requirements, not fall within an ineligible business category, be creditworthy and demonstrate a reasonable ability to repay.
SBA also identifies the requirement that the desired credit not be available on reasonable terms from non-federal, non-state and non-local government sources.
Why Should Borrowers Avoid Old Application Checklists?
The documents and underwriting steps for an SBA loan can depend on the size of the loan, lender processing method, ownership structure, use of funds and transaction type.
A checklist copied from an older article can therefore be useful as general preparation but should not be treated as the lender’s final document request.
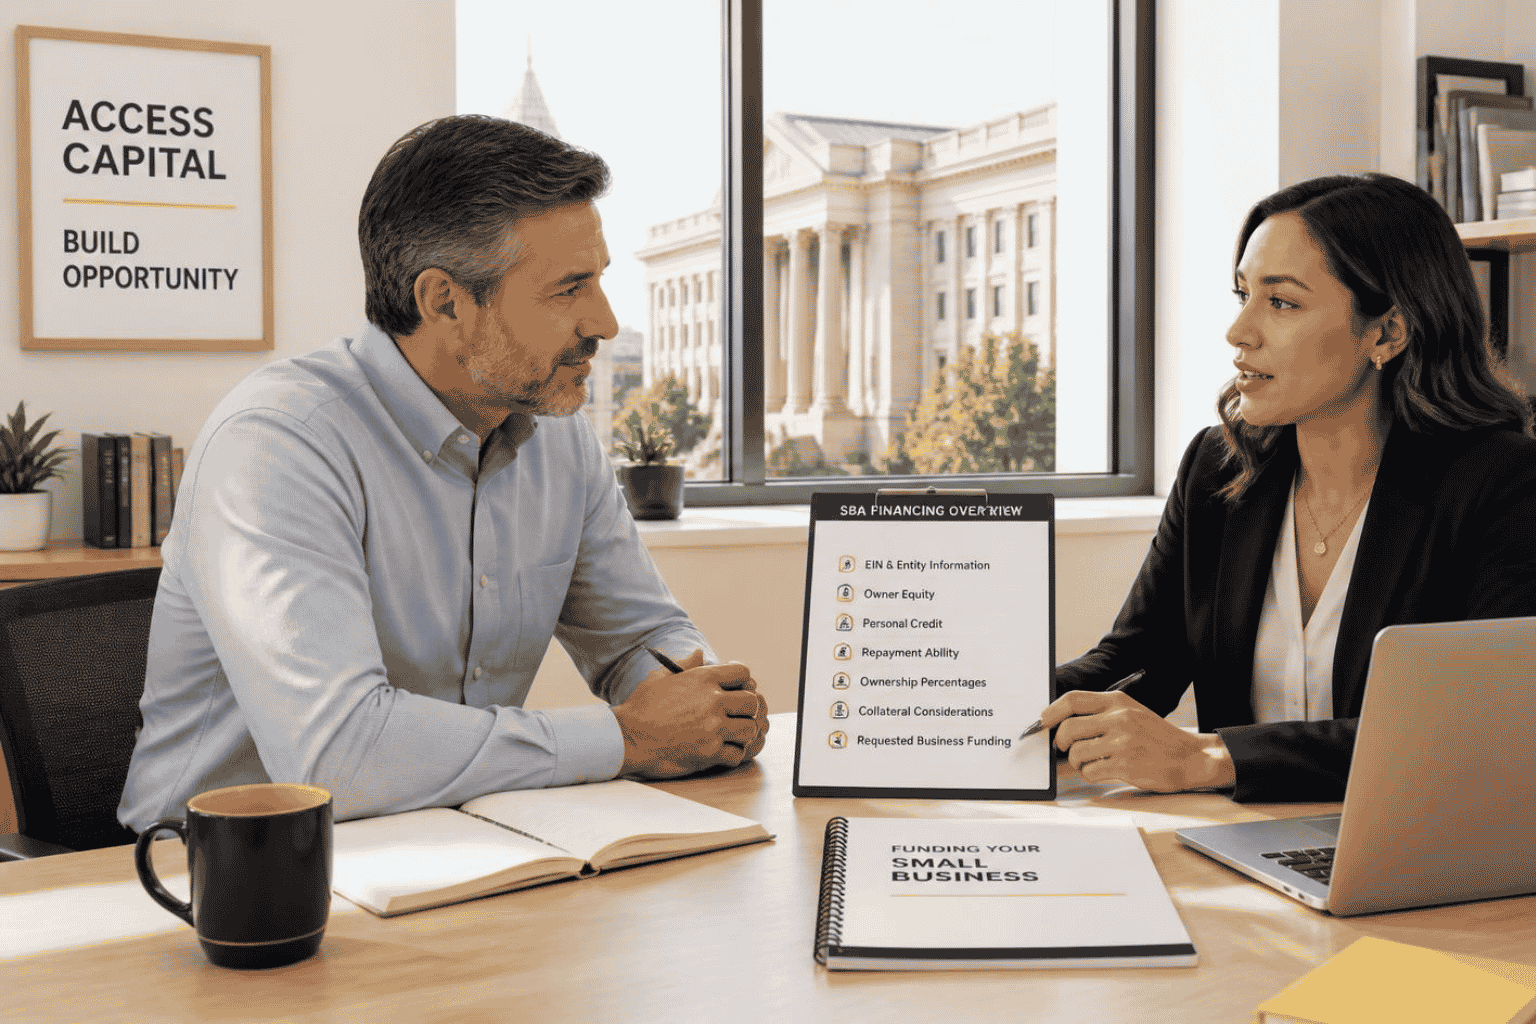
Start With Accurate Ownership Information
Before approaching the lender, know the legal business name, entity type, EIN, state of organization and ownership percentages.
Ownership details can affect required borrower information, guarantees and other aspects of the transaction.
Define the Use of Funds Precisely
“Business growth” is not a detailed funding purpose.
Identify whether the request involves acquisition financing, equipment, working capital, qualifying real estate, expansion or another specific business need.
The use of proceeds can affect the program structure, documentation and the financing category that should be evaluated.
Update the Financial Information Before Applying
Do not begin with revenue or debt numbers that are several months out of date if more current information is available.
Prepare recent business financial information, current debt balances and updated business banking information so the financing discussion reflects the company as it operates today.
Know Your Existing Business Debt
List current business loans, business credit cards and lines of credit with balances and applicable limits.
Existing obligations affect the repayment picture even when the company has strong revenue.
What About SBA’s Working Capital Pilot?
SBA’s current 7(a) information also continues to describe the Working Capital Pilot, a monitored line-of-credit program for qualifying growing small businesses.
SBA identifies businesses such as manufacturers, wholesalers and professional-services firms among potential users. Current guidance states that qualifying businesses generally need at least one year of operating history and must be able to produce timely financial statements, accounts receivable and accounts payable agings, and inventory reports where applicable.
Do Not Assume SBA Financing Is Automatically the Best Option
SBA-backed financing can be attractive for qualifying borrowers, but the correct funding path still depends on the business need, timing, documentation, borrower profile and transaction.
A company needing relatively small short-term capital quickly may have a different decision from a borrower financing a major acquisition, commercial property or long-term fixed asset.
What Should a Borrower Prepare Before the First Funding Discussion?
- Legal business name and EIN
- Entity type and formation date
- Ownership percentages
- Annual business revenue
- Current financial statements
- Business banking information
- Current credit profile
- Existing business debt
- Requested financing amount
- Specific use of funds
Current Procedures Make Accurate Preparation More Important
The effective SOP version is a lender-policy matter, not a reason for a business owner to become an SBA procedural expert.
The borrower’s job is to present accurate, current business information and a realistic financing request. The participating lender can then determine the documentation and processing requirements that apply to the specific loan.
FAQs
When did SBA SOP 50 10 8.1 become effective?
SBA lists Version 8.1 with technical updates as effective October 1, 2026 for the 7(a) and 504 loan programs.
Do borrowers apply directly to SBA for a 7(a) loan?
No. Borrowers apply through participating lenders, which determine the documents needed for the particular loan and processing method.
Should a borrower rely on an old SBA loan checklist?
Older checklists can provide general preparation guidance, but borrowers should confirm current requirements with the participating lender handling the application.
 SBA SOP 50 10 Version 8.1 became effective October 1, 2026 for the 7(a) and 504 loan programs.