Avoid These Business Funding Mistakes Before You Apply
What business funding mistakes should you avoid before applying? Common problems include requesting capital without a clear purpose, submitting incomplete financial information, misunderstanding cash flow, overlooking existing debt, and applying before the business is financially prepared.
A funding application is easier to evaluate when the business owner can clearly explain how much capital is needed, why it is needed, how the money will be used, what financial obligations already exist, and how the business expects to support repayment.
In this short educational video, EIN Business Funding (EINBF), part of Enterprise Industry Network (EIN), explains common business funding mistakes and how owners can improve funding readiness before submitting a financing request.
What Are Common Business Funding Mistakes?
Business owners sometimes begin the funding process before fully preparing the financial and operational information needed to support the request.
Common mistakes may include:
- Applying without knowing the exact amount of capital needed.
- Providing an unclear or vague use of funds.
- Submitting incomplete or disorganized financial records.
- Focusing only on revenue without understanding cash flow.
- Failing to review existing debt and repayment obligations.
- Providing inconsistent business information.
- Applying for funding that does not match the actual business need.
- Waiting until the business is under severe financial pressure before exploring options.
Mistake #1: Applying Without a Clear Use of Funds
Funding providers generally want to understand why the business needs capital and how the money will be used.
A request such as “we need more cash” may not provide enough context. A more specific funding purpose could include working capital, equipment, inventory, expansion, acquisition financing, refinancing, hiring, or another defined business objective.
Knowing the purpose of the capital can also help business owners determine which type of financing may be appropriate.
Mistake #2: Ignoring Cash Flow
Strong revenue does not automatically mean a company has strong cash flow. Businesses may generate substantial sales while experiencing cash shortages caused by slow receivables, high operating expenses, inventory requirements, seasonal fluctuations, or debt payments.
Before applying for financing, owners should understand how much cash enters the company, how much leaves, and whether the business can reasonably support additional financing obligations.
Mistake #3: Submitting Disorganized Financial Records
Incomplete or inconsistent financial information can make a funding request harder to evaluate.
Depending on the financing product and provider, business owners may need to prepare:
- Recent business bank statements.
- Profit-and-loss statements.
- Balance-sheet information.
- Business tax returns when requested.
- Debt schedules.
- Accounts receivable information.
- Documentation supporting the intended use of funds.
Organized records can help provide a clearer picture of business performance and funding readiness.
Mistake #4: Overlooking Existing Debt
Current loans, credit lines, leases, merchant financing, or other financial obligations can affect a new funding request.
Business owners should know their existing balances, monthly repayment requirements, maturity dates, and the effect those obligations have on cash flow.
Taking on additional capital without understanding current debt can create unnecessary financial pressure.
Mistake #5: Choosing Funding Based Only on the Amount Available
The largest approval is not automatically the best financing option.
Business owners should consider the complete structure of the funding, including:
- Total financing cost.
- Repayment frequency.
- Length of the financing term.
- Collateral or guarantee requirements.
- Impact on cash flow.
- Flexibility of the financing.
- How the capital supports the intended business objective.
Capital should fit the business need rather than creating obligations that are difficult to support.
Mistake #6: Waiting Until Funding Becomes an Emergency
Funding options can become more limited when a business waits until cash flow has deteriorated significantly or financial problems have already become severe.
Reviewing capital needs earlier can give business owners more time to organize records, understand available financing structures, compare options, and address financial weaknesses before they become urgent.
How to Improve Business Funding Readiness
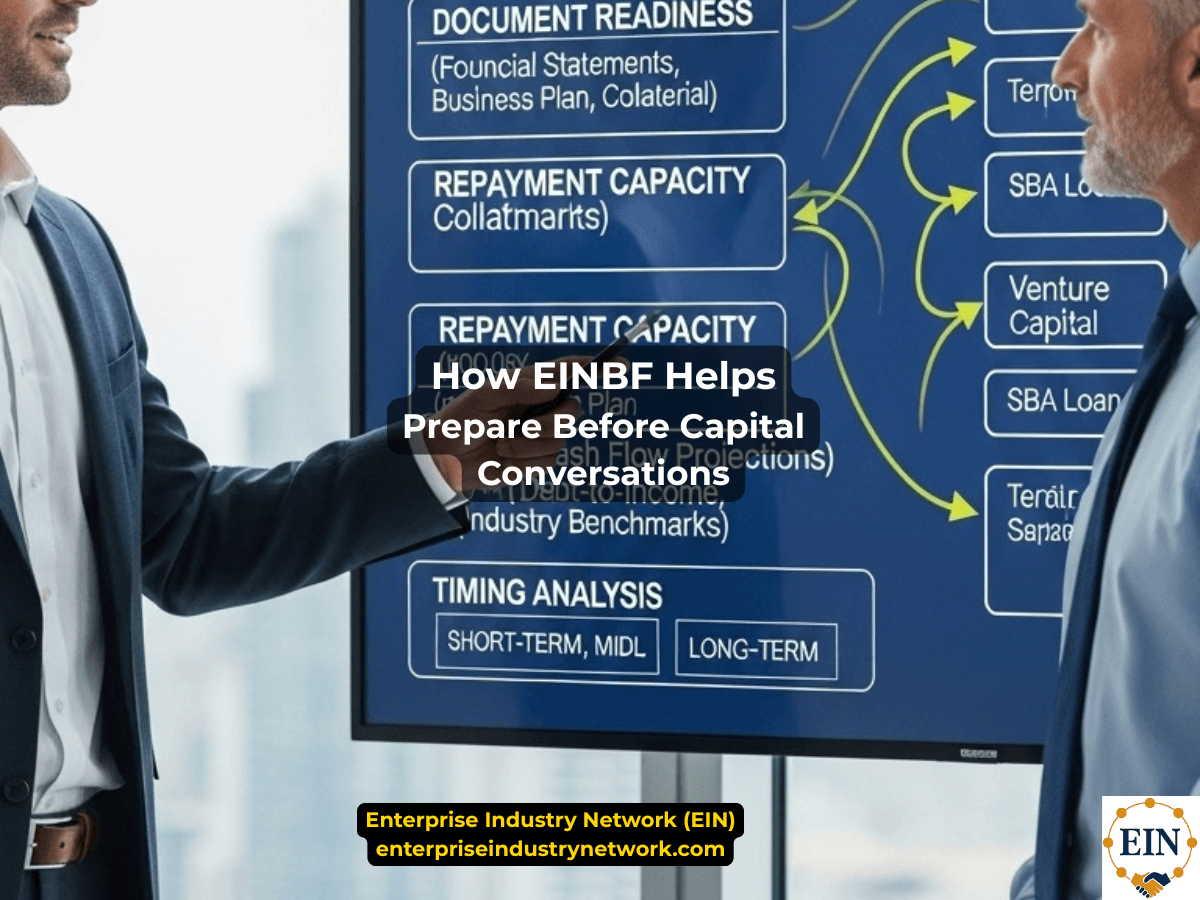
Funding readiness begins before an application is submitted. Business owners can prepare by reviewing the company’s financial position and clearly defining the funding request.
- Determine how much capital is actually needed.
- Define the exact use of funds.
- Review business cash flow.
- Organize financial records.
- Understand existing debt obligations.
- Review recent business bank activity.
- Make sure business information is accurate and consistent.
- Compare financing structures based on the actual business need.
Explore Business Funding with EIN Business Funding
EIN Business Funding (EINBF), part of Enterprise Industry Network, helps business owners understand funding readiness and explore potential financing options based on their business profile, capital needs, financial position, and intended use of funds.
Depending on the business and funding purpose, options may include working capital, business lines of credit, equipment financing, acquisition financing, refinancing, growth capital, and other business financing solutions.
Prepare Before You Apply
Avoid common funding mistakes by understanding your capital needs, financial position, cash flow, and existing obligations before submitting a funding request.
Frequently Asked Questions
What are the biggest mistakes businesses make when applying for funding?
Common mistakes include applying without a clear use of funds, misunderstanding cash flow, submitting incomplete financial records, overlooking existing debt, and choosing financing based only on the amount offered.
Why does cash flow matter when applying for business funding?
Cash flow can help show whether a business has enough available cash to support operating expenses and additional financing obligations even when revenue is strong.
Should I organize my financial records before applying?
Yes. Organized financial records can help funding providers understand the business more clearly and may reduce delays caused by missing or inconsistent information.
Can existing debt affect a new funding request?
Yes. Existing loans and financial obligations can affect available cash flow and may influence whether additional financing appears manageable for the business.
How can I prepare for business funding before applying?
Clarify how much capital you need, define the use of funds, review cash flow, organize financial records, understand existing debt, review bank activity, and make sure business information is accurate and consistent.
 Business owners can improve funding readiness by clarifying the use of funds, understanding cash flow, organizing financial records, and reviewing existing debt before applying.