Business Funding Readiness Checklist: What to Fix Before You Apply
What should a business fix before applying for funding? A company may need capital for growth, payroll, equipment, inventory, an acquisition, refinancing, or working capital, but urgency alone does not make the business funding-ready.
Funding readiness is about presenting a company that lenders and funding sources can understand, evaluate, and assess with reasonable confidence. That means having clear financial records, consistent information, a defined funding purpose, realistic repayment expectations, and a capital request that fits the company’s broader financial position.
In this long-form educational video, EIN Business Funding (EINBF), part of Enterprise Industry Network (EIN), explains the practical areas business owners should review and fix before applying for capital.
What Does Business Funding Readiness Mean?
Business funding readiness means preparing the company before approaching lenders or funding providers.
A funding-ready business should generally be able to explain:
- How much capital is needed.
- Why the business needs the funding.
- How the money will be used.
- Current revenue and cash flow.
- Existing debt and obligations.
- How repayment is expected to be supported.
- Which documents are available.
- Which type of financing may fit the need.
1. Fix Unclear Financial Records
Disorganized financial records can make a funding request difficult to evaluate.
Before applying, business owners should review whether their financial information is complete, understandable, and internally consistent.
That may include:
- Profit-and-loss statements.
- Balance sheets.
- Business bank statements.
- Tax returns when requested.
- Accounts receivable records.
- Accounts payable records.
- Debt schedules.
The objective is not perfection. The objective is clarity.
2. Fix Inconsistent Revenue Information
Lenders may compare revenue across bank statements, financial statements, tax records, and application materials.
If the numbers do not align, the business should be prepared to explain why.
Potential causes of inconsistencies may include:
- Cash versus accrual accounting.
- Seasonality.
- One-time revenue events.
- Recent growth or decline.
- Timing differences.
- Incomplete bookkeeping.
Unexplained inconsistencies can create additional underwriting questions and delays.
3. Fix Weak Cash-Flow Visibility
Revenue alone does not show whether the business has enough available cash to support financing.
Owners should understand:
- How much cash enters the business.
- How much leaves each month.
- Payroll requirements.
- Inventory needs.
- Supplier payments.
- Debt service.
- Seasonal fluctuations.
- Customer-payment timing.
Better cash-flow visibility helps both the business owner and the funding provider understand repayment capacity.
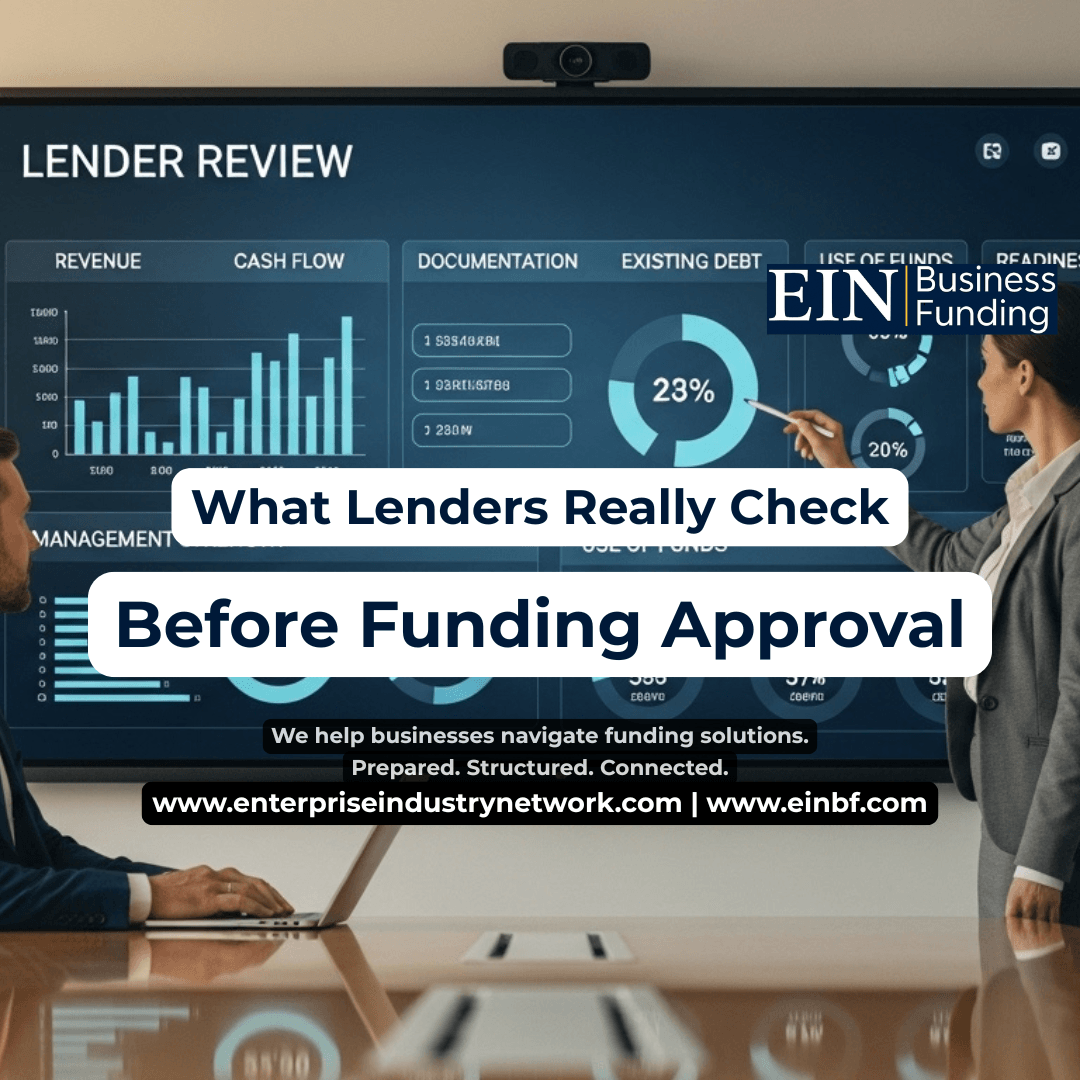
4. Review Existing Debt Before Adding More
A business should know exactly what financial obligations already exist before requesting additional capital.
Owners should review:
- Outstanding loan balances.
- Business lines of credit.
- Equipment financing.
- Lease obligations.
- Merchant financing.
- Monthly repayment amounts.
- Interest or financing costs.
- Collateral or guarantees.
New funding should fit around existing obligations rather than create unsustainable repayment pressure.
5. Fix an Undefined Use of Funds
A vague funding request can make it harder for a lender to understand why capital is needed.
Business owners should be able to clearly state whether the funding is intended for:
- Working capital.
- Payroll.
- Inventory.
- Equipment.
- Expansion.
- Technology.
- Marketing.
- Acquisition financing.
- Refinancing.
- Other qualified business purposes.
The more specific the use of funds, the easier it becomes to evaluate whether the requested financing structure fits the need.
6. Fix an Unrealistic Funding Amount
Requesting more capital than the business needs can increase financing cost and repayment pressure.
Requesting too little may fail to solve the underlying problem.
A stronger funding request should be based on:
- The actual business need.
- Existing available cash.
- Expected project or operating costs.
- Working-capital requirements.
- Repayment capacity.
- Timing.
7. Fix Unclear Repayment Capacity
A business should understand how additional financing will be repaid before taking on the obligation.
That means evaluating whether cash flow can support:
- Existing operating expenses.
- Payroll.
- Taxes.
- Supplier payments.
- Current debt.
- The proposed new financing obligation.
Funding should not create a repayment structure that leaves the business with too little operating flexibility.
8. Fix Bank Activity Issues Before Applying
Business bank activity can be an important part of lender review.
Owners may want to identify and understand:
- Frequent overdrafts.
- Returned payments.
- Irregular deposits.
- Large unexplained transactions.
- Transfers between accounts.
- Existing lender withdrawals.
- Seasonal balance changes.
Unusual activity is not automatically disqualifying, but it should be understandable and explainable.
9. Fix Incomplete Documentation
Missing documents can slow the funding process significantly.
Depending on the financing product, business owners may need:
- Recent bank statements.
- Financial statements.
- Tax records.
- Debt schedules.
- Ownership information.
- Entity documents.
- Accounts receivable data.
- Supporting records for the intended use of funds.
Preparing these materials before applying can improve both speed and clarity.
10. Fix Unrealistic Financial Projections
Projections can be useful when capital is intended for expansion, hiring, equipment, an acquisition, or another growth initiative.
However, projections should be realistic and based on reasonable assumptions.
Business owners should be able to explain:
- Expected revenue growth.
- Expected expenses.
- New payroll requirements.
- Working-capital needs.
- Timing of expected returns.
- How financing payments fit into the forecast.
11. Fix an Inappropriate Funding Structure
Funding readiness also means choosing a financing structure that matches the business need.
Different situations may call for different options:
- Working capital for short-term operating needs.
- A business line of credit for recurring liquidity needs.
- Equipment financing for machinery or productive assets.
- Invoice financing for eligible receivables.
- Acquisition financing for buying an existing business.
- Refinancing for restructuring current obligations.
The business should not force every need into the same product.
12. Fix Unexplained Business Risks
Lenders may want to understand material risks that could affect financial performance.
Examples can include:
- Customer concentration.
- Supplier dependence.
- Seasonality.
- Recent revenue decline.
- Management changes.
- Pending legal matters.
- Large upcoming expenses.
- Operational disruptions.
Being transparent about risk can be more effective than allowing the lender to discover unexplained issues later in underwriting.
13. Review Credit Before Applying
Depending on the lender and financing product, business credit, personal credit, or both may be considered.
Owners should know whether there are:
- Late payments.
- Collections.
- High utilization.
- Recent credit inquiries.
- Bankruptcies.
- Other material credit events.
Understanding the credit profile beforehand can help set more realistic expectations around available funding paths.
14. Fix the Timing of the Funding Request
Businesses often have more options when they prepare before capital becomes urgent.
Waiting until payroll is due, cash is nearly exhausted, or a major obligation is already overdue can reduce flexibility.
Earlier preparation gives the business time to:
- Organize documents.
- Improve bookkeeping.
- Review cash flow.
- Address debt.
- Compare funding options.
- Clarify the funding purpose.
- Strengthen the overall request.
15. Make the Business Easy to Understand
A strong funding request should tell a clear financial story.
A lender should be able to understand:
- What the business does.
- How it generates revenue.
- How much capital is needed.
- What the funding will accomplish.
- What obligations already exist.
- How repayment is expected to work.
- What risks may affect performance.
Clear information can improve the quality of the funding conversation even though it does not guarantee approval.
Funding Readiness Is Different from Funding Approval
A business can be well prepared and still not meet a specific lender’s underwriting requirements.
Different lenders may have different standards relating to revenue, cash flow, time in business, credit, industry, collateral, funding amount, and repayment structure.
Funding readiness improves preparation. It does not create automatic approval.
How EIN Business Funding Helps Businesses Prepare
EIN Business Funding (EINBF), part of Enterprise Industry Network, helps business owners approach capital with greater preparation and clarity by reviewing funding needs, cash flow, financial information, existing obligations, funding purpose, and potential financing paths.
Depending on the company and funding need, potential options may include working capital, business loans, business lines of credit, equipment financing, invoice financing, acquisition financing, refinancing, and other qualified business funding structures.
The objective is to help businesses become easier to understand, better prepared for financing conversations, and more informed before making a capital decision.
Fix the Funding Gaps Before You Apply
Review your financial records, cash flow, debt, bank activity, documentation, funding purpose, repayment capacity, and financing structure before submitting a business funding request.
Frequently Asked Questions
What should I fix before applying for business funding?
Business owners should review financial records, revenue consistency, cash flow, existing debt, bank activity, credit, documentation, funding purpose, requested amount, and repayment capacity before applying.
What does funding readiness mean?
Funding readiness means preparing the business and its financial information so lenders and funding providers can clearly understand the company, capital need, financial position, and repayment capacity.
Can poor bookkeeping affect business funding?
Yes. Incomplete or inconsistent financial records can create underwriting questions, delays, and difficulty verifying revenue, expenses, debt, and cash flow.
Why is a clear use of funds important?
A defined funding purpose helps the provider understand why capital is needed, whether the requested amount is reasonable, and which financing structure may fit the business need.
Does being funding-ready guarantee approval?
No. Funding readiness improves preparation, but approval still depends on the lender’s underwriting standards, product requirements, business profile, and financial risk assessment.
When should a business start preparing for funding?
Ideally, preparation should begin before capital becomes urgent so the business has time to organize documentation, review cash flow, understand debt, clarify funding needs, and compare financing options.
 Before applying for business funding, owners should review financial records, cash flow, existing obligations, bank activity, credit, documentation, funding purpose, and repayment capacity.