Working Capital Loans: What They Can Be Used For and When They Make Sense
What can a working capital loan be used for? Business owners may use working capital financing to help cover short-term operating needs such as payroll, inventory, supplier payments, rent, seasonal expenses, marketing, and temporary cash-flow gaps.
Working capital can support day-to-day business stability, but the purpose of the funding matters. Owners should understand how much capital is needed, how long the need is expected to last, how repayment may affect cash flow, and whether the financing is solving a temporary gap or masking a deeper financial problem.
In this short educational video, EIN Business Funding (EINBF), part of Enterprise Industry Network (EIN), explains how working capital financing works and the factors business owners should evaluate before applying.
What Is Working Capital Financing?
Working capital financing is generally used to support short-term operating needs rather than long-term investments such as purchasing real estate or completing a major acquisition.
Businesses may use working capital to help manage the gap between incoming revenue and outgoing expenses.
Common uses can include:
- Payroll.
- Inventory purchases.
- Supplier and vendor payments.
- Rent and utilities.
- Seasonal operating expenses.
- Marketing and sales activities.
- Short-term cash-flow gaps.
- Unexpected operating costs.
When Can a Working Capital Loan Help?
Working capital financing may be useful when a business has a temporary need for liquidity but expects normal operations and revenue to support repayment.
Examples may include:
- A seasonal business preparing inventory before peak demand.
- A company waiting for customer invoices to be paid.
- A business covering payroll while receivables are outstanding.
- A company increasing inventory to support confirmed demand.
- A business managing a temporary mismatch between expenses and incoming cash.
The key is that the financing should support a defined short-term need and fit the company’s broader cash-flow position.
Revenue and Cash Flow Are Not the Same
A business may generate strong revenue and still experience working-capital pressure.
For example, customers may take 30, 60, or 90 days to pay invoices while payroll, rent, suppliers, and other expenses must be paid sooner.
This timing difference can create a cash-flow gap even when the company is profitable on paper.
Working capital financing may help manage that gap, but owners should understand how quickly expected cash inflows are likely to arrive.
Working Capital for Payroll
Payroll is one of the most time-sensitive operating expenses for many businesses. A temporary delay in customer payments or a seasonal revenue dip can create short-term payroll pressure.
Working capital may help bridge that gap, but recurring reliance on borrowed funds for payroll can also indicate a deeper cash-flow problem.
Owners should distinguish between a temporary timing issue and an ongoing operating shortfall.
Working Capital for Inventory
Businesses that need to purchase inventory before generating revenue may use working capital financing to help fund those purchases.
This can be especially relevant for seasonal businesses, retailers, wholesalers, manufacturers, and companies responding to increased customer demand.
Before borrowing for inventory, business owners should consider:
- How quickly the inventory is expected to sell.
- Expected gross margins.
- Supplier payment terms.
- Seasonality.
- Storage and carrying costs.
- How financing payments affect cash flow.
Working Capital for Vendor and Supplier Payments
Maintaining strong supplier relationships can be important to business continuity.
Working capital financing may help a company manage temporary payment timing issues or take advantage of supplier opportunities, depending on the business need.
However, owners should avoid repeatedly using new financing simply to cover obligations that the company’s normal operations cannot support.
Working Capital for Seasonal Businesses
Seasonal businesses may experience predictable periods when expenses increase before revenue arrives.
For example, a company may need to hire staff, buy inventory, increase marketing, or prepare facilities ahead of its busiest season.
Short-term working capital may help support those costs when the business has a clear understanding of its seasonal revenue cycle and repayment capacity.
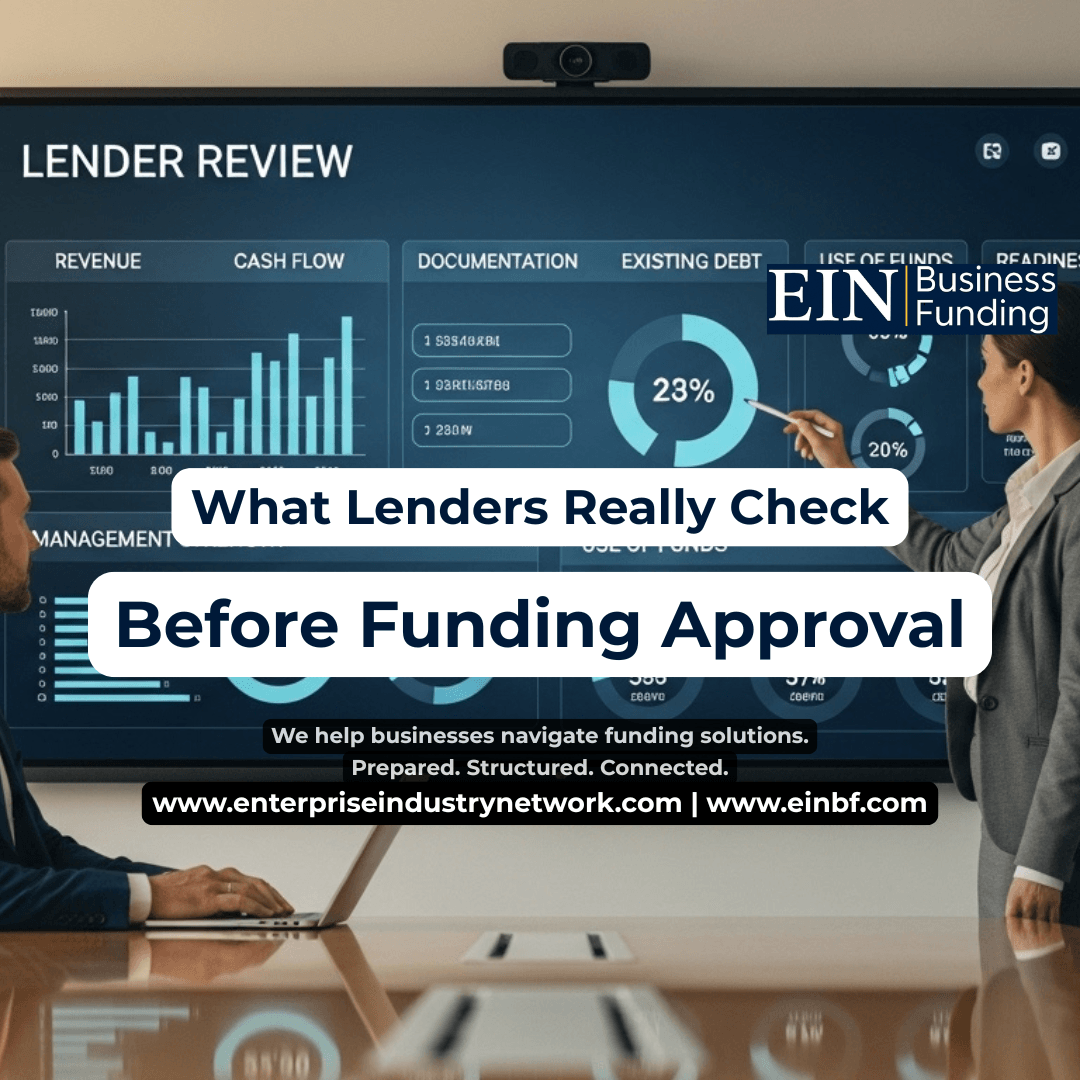
How Lenders May Evaluate Working Capital Requests
Depending on the financing product and provider, the review may include:
- Business revenue.
- Cash-flow consistency.
- Business bank statements.
- Time in business.
- Existing debt.
- Credit profile.
- Requested amount.
- Use of funds.
- Current repayment obligations.
- Overall funding readiness.
Different providers may use different underwriting standards, so available options can vary from one business to another.
How Much Working Capital Does a Business Need?
Business owners should avoid borrowing more than necessary simply because a larger amount may be available.
A better approach is to estimate the actual operating gap and determine:
- How much capital is required.
- What expenses the funds will cover.
- How long the financing is needed.
- When expected revenue or receivables should arrive.
- How repayment will affect monthly cash flow.
The funding amount should fit the business need and repayment capacity.
Working Capital Loan vs Business Line of Credit
A working capital loan may provide a lump sum that is repaid according to agreed terms. A business line of credit may provide access to a revolving amount of capital that can be drawn when needed, subject to the provider’s terms.
The more suitable structure depends on whether the business needs a one-time amount or recurring access to short-term liquidity.
When Working Capital Financing May Not Be the Right Solution
Working capital financing may not solve the underlying problem if the business is consistently losing money, margins are too low, expenses are unsustainable, or debt obligations already exceed the company’s repayment capacity.
Before borrowing, owners should ask whether the financing is addressing a temporary need or delaying a larger financial issue.
Questions to Ask Before Taking a Working Capital Loan
- What specific expense or cash-flow gap will the funding cover?
- How much capital is actually needed?
- How long will the need last?
- When is expected cash expected to arrive?
- Can the business comfortably support repayment?
- What is the total financing cost?
- How frequently are payments required?
- Are collateral or guarantees required?
- Will the financing improve operations or simply postpone financial pressure?
Explore Working Capital Options with EIN Business Funding
EIN Business Funding (EINBF), part of Enterprise Industry Network, helps business owners explore working capital and other financing options based on their business profile, funding need, revenue, cash flow, time in business, and overall readiness.
The right working-capital strategy should support a defined business need while preserving enough cash flow for day-to-day operations and future obligations.
Explore Working Capital Options
Need short-term capital for payroll, inventory, vendors, seasonal expenses, or a temporary cash-flow gap? Explore business funding options based on your company’s needs and readiness.
Frequently Asked Questions
What can a working capital loan be used for?
Working capital may be used for short-term operating expenses such as payroll, inventory, vendor payments, rent, seasonal expenses, marketing, or temporary cash-flow gaps, depending on the financing terms.
Is working capital the same as a business loan?
Working capital financing is a broad category of business funding used mainly for short-term operating needs. The specific product may be structured as a term loan, line of credit, or another financing arrangement.
Can working capital be used for payroll?
It may be used for payroll in some situations, particularly when the business is managing a temporary cash-flow timing gap. Repeated borrowing for payroll, however, may indicate a deeper financial issue.
Can working capital be used to buy inventory?
Yes, inventory is a common potential use, especially when a business needs to purchase goods before receiving revenue from future sales.
How do lenders determine working capital eligibility?
Funding providers may review revenue, cash flow, bank activity, time in business, existing debt, credit profile, requested amount, intended use of funds, and other underwriting factors.
How much working capital should a business borrow?
The amount should generally reflect the actual short-term operating need and the company’s ability to support repayment without creating excessive cash-flow pressure.
 Working capital financing can help businesses manage payroll, inventory, vendors, seasonal expenses, and temporary cash-flow gaps when the need is short term and repayment fits the company’s financial position.