Business Acquisition Loan With Existing Company Debt: What Buyers Need to Recalculate Before Closing
A buyer can agree on a reasonable purchase price and still discover that existing company debt materially changes the acquisition financing required to close the transaction.
Loans, equipment obligations, credit lines and other business liabilities can affect both the amount paid at closing and the cash flow available to support new acquisition debt.
If you have identified a business and are already reviewing the company’s existing obligations, complete the EIN Business Funding Quick Lead Pre-Qualification using the purchase price, buyer contribution and estimated financing requirement.
Start With a Complete Debt Schedule
Do not rely only on a balance-sheet total. Build a list of the company’s open financing obligations.
- Business term loans
- Business lines of credit
- Equipment loans or leases
- Vehicle financing
- Business credit-card balances
- Other documented business debt
For each obligation, identify the lender, current balance, applicable limit, open date and expected treatment at closing.
Will the Debt Be Paid Off at Closing?
This question can materially affect the transaction.
If debt must be satisfied at closing, the seller’s net proceeds may be lower than the headline purchase price. If an obligation remains with the acquired business, the buyer needs to understand how the continuing payment affects future cash flow.
Existing Debt Can Reduce Acquisition Debt Capacity
The business may have sufficient revenue to support operations but less capacity to support a new acquisition loan once existing obligations are included.
A buyer should evaluate the company’s sustainable cash flow after ordinary expenses and continuing debt payments.
Do Not Double-Count Debt in the Purchase Structure
The purchase agreement and financing model should clearly show how liabilities are being treated.
Buyers should understand whether the agreed purchase price assumes a debt-free transaction, includes certain assumed liabilities or requires specific obligations to be paid before ownership transfers.
These are transaction-specific issues that should be addressed clearly with the appropriate legal, accounting and transaction professionals.
How Does Debt Affect the Buyer Contribution?
If additional funds are required to satisfy obligations at closing, the buyer may need more capital than originally expected.
Alternatively, the transaction may need to be restructured so that the purchase price, seller proceeds, buyer contribution and outside financing remain realistic.
Why Cash Flow Must Be Recalculated
Historical earnings may not represent the buyer’s future cash flow if financing obligations change after closing.
Remove debt that will disappear, include debt that will remain and add the expected acquisition-financing payment when analyzing the post-closing business.
What About Equipment Debt?
Equipment financing deserves particular attention because the underlying asset may be essential to business operations.
The buyer should understand whether the obligation will be paid off, refinanced or otherwise addressed as part of the transaction.
Do not assume ownership of the equipment automatically means the financing attached to it transfers on the same terms.
Working Capital Still Needs Its Own Budget
Paying off existing debt at closing does not eliminate the need for operating cash.
The acquired company may need immediate liquidity for payroll, inventory, supplier payments, maintenance, insurance and other normal expenses.
The buyer should therefore calculate post-closing working capital separately from debt payoff and purchase consideration.
What Should Buyers Recalculate?
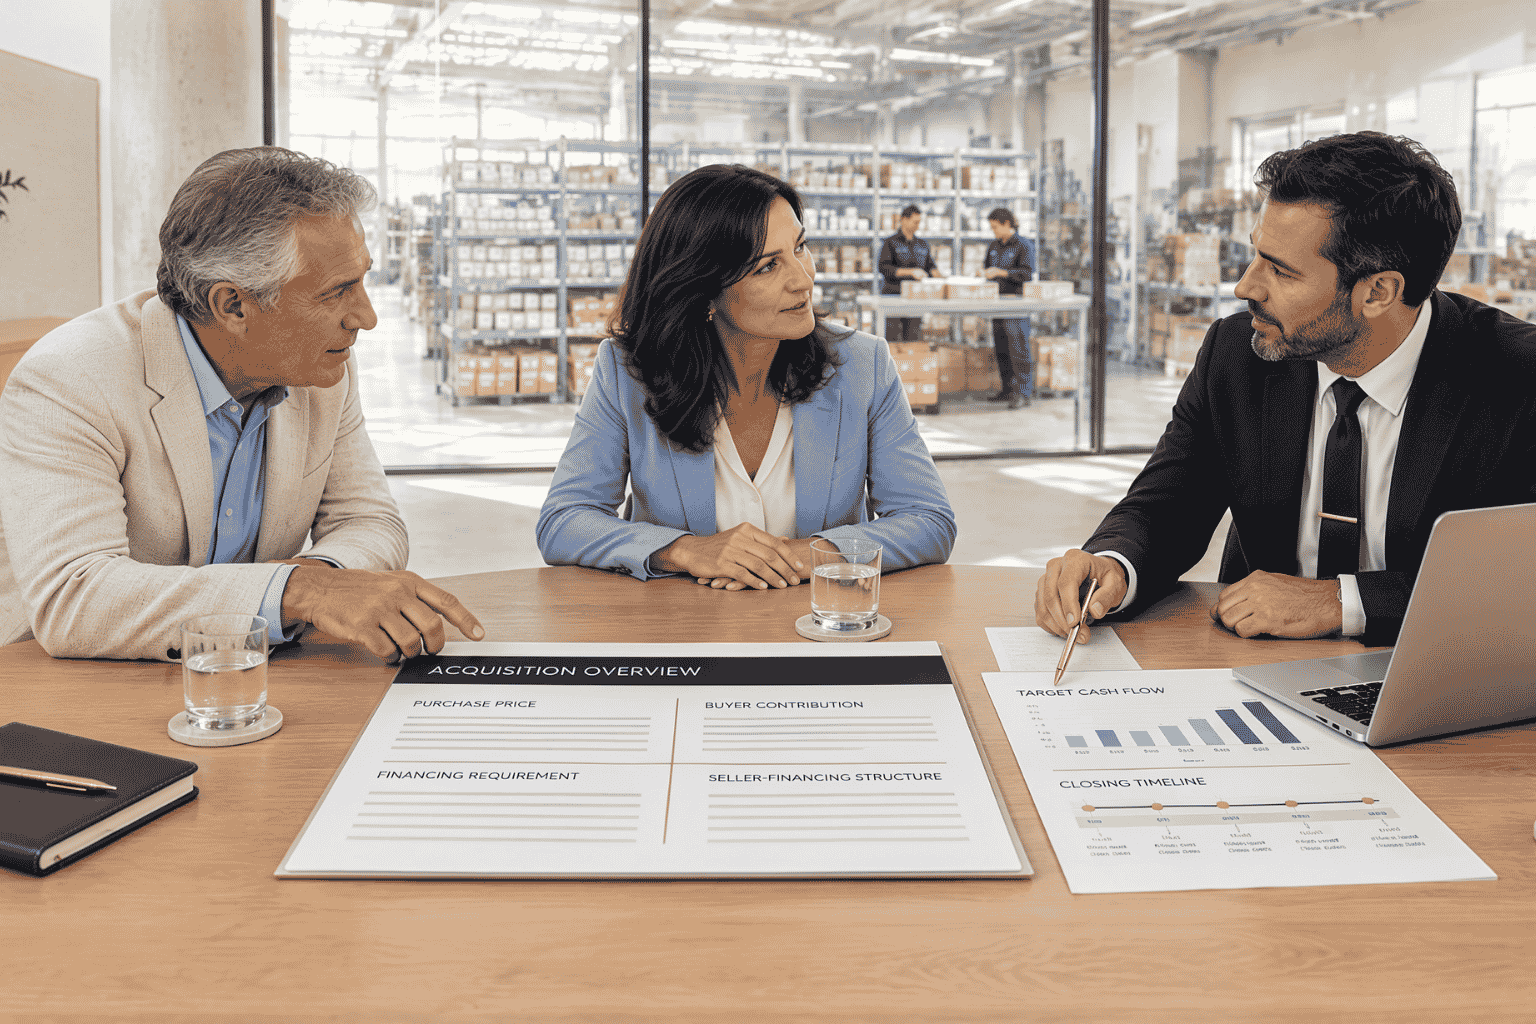
- Purchase price
- Existing debt payoff
- Debt remaining after closing
- Buyer contribution
- Seller financing, if any
- Outside acquisition financing required
- Post-closing debt payments
- Working-capital requirement
What Should Be Prepared for Funding Review?
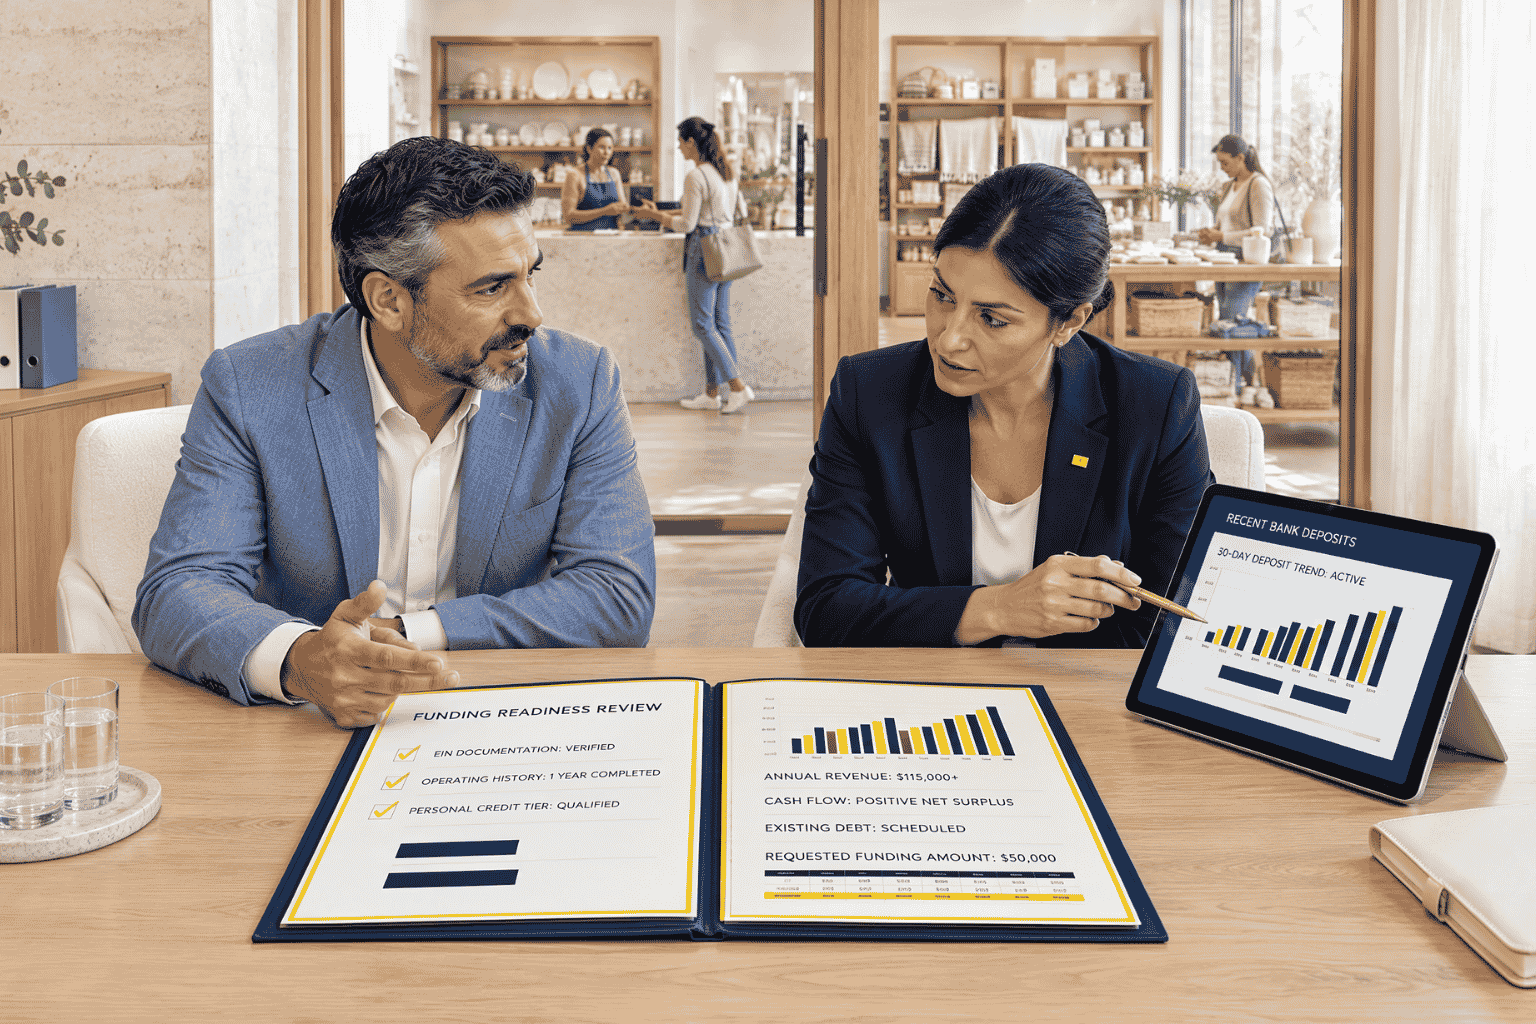
In addition to the transaction numbers, have current buyer credit information, ownership details, target-company annual revenue, cash-flow information and existing debt records organized.
The more accurately the transaction is presented, the easier it is to identify whether the proposed financing structure is realistic.
Do Not Wait Until Closing to Discover the Debt Problem
Existing debt should be reviewed while the buyer is evaluating the business—not after financing, legal documents and closing preparation are already advanced.
Discovering an unexpected obligation early gives the parties more time to adjust valuation, financing or transaction structure.
A Good Acquisition Model Shows What the Business Looks Like After Closing
The goal is not simply to prove that the purchase price can be funded. The buyer needs to understand whether the acquired company remains financially healthy after old obligations are addressed and new acquisition debt begins.
That post-closing picture is often more important than the headline transaction value.
FAQs
Can existing company debt affect a business acquisition loan?
Yes. Existing obligations can affect cash flow, the amount required at closing and the company’s capacity to support new acquisition financing.
Should business debt be paid off before closing?
That depends on the transaction and the specific obligation. Buyers should clearly understand which debts will be satisfied, remain with the business or otherwise be addressed at closing.
Should working capital be calculated separately from debt payoff?
Yes. The acquired company still needs operating cash after closing even if existing liabilities are paid off as part of the transaction.
 Existing company obligations can change both the acquisition funding requirement and the cash flow available after closing.