Business Funding: What to Know Before You Apply
What should a business owner know before applying for business funding? The strongest funding decisions usually begin before an application is submitted. Owners should understand why capital is needed, how much is required, how the funds will be used, what the business can realistically support, and which financing structures may fit the situation.
Business funding can support working capital, equipment purchases, expansion, inventory, acquisitions, refinancing, cash-flow needs, and other qualified business purposes. But different financing products have different costs, repayment structures, eligibility requirements, and implications for the business.
In this long-form educational video, EIN Business Funding (EINBF), part of Enterprise Industry Network (EIN), explains the essential considerations business owners should understand before seeking capital.
Start With the Business Need Before the Funding Product
A common mistake is starting with a loan product before clearly defining the business need.
Before comparing financing options, business owners should first determine:
- How much capital is actually needed.
- Why the funding is required.
- How the money will be used.
- Whether the need is short term or long term.
- When the capital is required.
- How the financing is expected to benefit the business.
A clearly defined funding purpose can make it easier to identify financing that aligns with the company rather than simply accepting the first available option.
Understand the Difference Between Revenue and Cash Flow
Strong revenue does not automatically mean a business is financially ready for additional financing.
Revenue represents the income generated by the business, while cash flow reflects how money actually moves through the company after payroll, suppliers, rent, debt payments, taxes, inventory, and other operating expenses.
A company may generate substantial revenue while still experiencing cash-flow pressure because customers pay slowly, margins are weak, expenses are high, or existing debt consumes too much liquidity.
Before seeking funding, owners should understand whether current cash flow can reasonably support additional repayment obligations.
Know How Much Business Funding You Really Need
Borrowing more than necessary can increase financing costs and place unnecessary pressure on cash flow.
Borrowing too little may fail to solve the original business need.
A stronger funding request is based on a realistic calculation of:
- The specific expense or project being funded.
- Existing available cash.
- The amount that must come from external financing.
- Expected timing of the expenditure.
- Additional working-capital needs.
- The company’s repayment capacity.
Define the Use of Funds Clearly
Funding providers generally want to understand how the requested capital will be used.
Common funding purposes may include:
- Working capital.
- Inventory purchases.
- Payroll.
- Equipment financing.
- Technology upgrades.
- Business expansion.
- Marketing and sales initiatives.
- Business acquisition financing.
- Refinancing existing debt.
- Other qualified operating or growth needs.
A clear use of funds can also help determine which financing structure may be more suitable.
Prepare Your Financial Documents Before You Apply
Funding readiness includes having financial and business records organized before the application process begins.
Depending on the provider and financing product, documentation may include:
- Recent business bank statements.
- Profit-and-loss statements.
- Balance sheets.
- Business tax returns when requested.
- Existing debt schedules.
- Accounts receivable information.
- Ownership and formation documents.
- Documents supporting the intended use of funds.
Complete and consistent information can help funding providers better understand the business and reduce avoidable delays caused by missing documentation.
Review Existing Business Debt
Existing financing obligations can materially affect both funding eligibility and repayment capacity.
Owners should understand:
- Outstanding loan balances.
- Monthly payment obligations.
- Interest rates or financing costs.
- Remaining repayment periods.
- Business liens or collateral.
- Personal guarantees.
- Lines of credit currently in use.
Taking on additional capital without understanding current obligations can create unnecessary financial pressure.
Compare Business Funding Options
Different funding structures are designed for different business needs.
Depending on the business profile and capital requirement, owners may explore:
- Working-capital financing.
- Business term loans.
- Business lines of credit.
- Equipment financing.
- Invoice or receivables financing.
- Business acquisition financing.
- SBA-related financing where applicable.
- Refinancing.
- Other business financing structures.
The objective should not be to find the largest approval. It should be to identify financing that appropriately matches the use of funds, repayment capacity, timing, and broader business strategy.
Understand the Total Cost of Financing
The monthly payment is only one part of the financing decision.
Business owners should review:
- Interest or financing charges.
- Origination fees.
- Closing costs.
- Service fees.
- Repayment frequency.
- Length of the financing term.
- Prepayment provisions.
- Collateral requirements.
- Personal guarantees.
- Total repayment amount.
A financing option with a lower monthly payment may still cost more overall if repayment continues for a significantly longer period.
Match Repayment to Business Cash Flow
A funding structure should fit the way the business generates cash.
For example, a seasonal company may have very different repayment needs from a business with stable monthly recurring revenue.
A company whose customers pay on 60- or 90-day terms may also need a different structure from a retail business that receives payment immediately.
Repayment frequency and timing should therefore be evaluated against the company’s actual cash-flow cycle.
When Working Capital Financing May Make Sense
Working capital financing can help support short-term operating needs such as payroll, inventory, vendor payments, seasonal expenses, or temporary cash-flow gaps.
It may be useful when the business has a clearly defined short-term need and sufficient expected cash flow to support repayment.
However, repeatedly borrowing to cover ongoing losses may indicate a deeper financial problem rather than a temporary working-capital need.
When a Business Line of Credit May Make Sense
A business line of credit may offer flexible access to capital up to an approved limit.
It may be suitable for recurring or unpredictable short-term needs where the business does not need the full amount of financing at once.
Business owners should still use revolving credit with discipline and understand how balances, fees, repayment, and financing costs affect cash flow.
When Equipment Financing May Make Sense
Equipment financing may allow a business to acquire productive assets while preserving more cash for day-to-day operations.
This may include machinery, commercial vehicles, technology systems, restaurant equipment, construction equipment, medical equipment, or other qualified business assets.
Owners should compare the useful life of the equipment, expected return on investment, total financing cost, and cash-flow impact before proceeding.
When Acquisition Financing May Be Needed
Buying an existing business often requires a broader financing structure.
Potential components may include:
- Buyer equity.
- Bank or SBA-style financing.
- Seller financing.
- Investor or partner capital.
- Asset-based financing.
- Post-closing working capital.
Acquisition financing should consider not only how to fund the purchase price, but also whether the acquired business will have sufficient liquidity to operate after closing.
Do Not Apply Only Because Funding Is Available
Available capital is not automatically good capital.
Business owners should ask whether the financing creates enough value to justify its cost and repayment obligation.
Before accepting funding, consider:
- What business outcome will the capital create?
- How quickly should that benefit appear?
- Can the business support repayment if results are slower than expected?
- Will the financing restrict future borrowing?
- Could the new debt reduce financial flexibility?
Prepare Before the Funding Need Becomes Urgent
Businesses often have more flexibility when they seek capital before financial pressure becomes severe.
Preparing early gives owners time to:
- Organize documentation.
- Review cash flow.
- Understand existing debt.
- Correct inconsistencies.
- Compare financing alternatives.
- Clarify the use of funds.
- Improve overall funding readiness.
How EIN Business Funding Helps Businesses Prepare for Capital
EIN Business Funding (EINBF), part of Enterprise Industry Network, helps business owners and buyers better understand funding readiness and explore financing options based on business profile, financial position, capital need, cash flow, timing, and intended use of funds.
Potential financing needs may include working capital, business lines of credit, equipment financing, invoice financing, acquisition financing, refinancing, growth capital, and other qualified business funding requirements.
The objective is to help businesses approach capital with greater clarity and preparation rather than pressure to accept the first financing option available.
Prepare Before You Apply for Business Funding
Clarify how much capital you need, understand your cash flow, organize your financial information, and explore funding options that fit the business before submitting a request.
Frequently Asked Questions
What should I know before applying for business funding?
Business owners should understand how much capital is needed, the intended use of funds, revenue, cash flow, existing debt, repayment capacity, financing costs, and which documents may be required before applying.
What documents are commonly required for business funding?
Requirements vary, but funding providers may request business bank statements, financial statements, tax returns, debt information, ownership records, and supporting documents related to the funding purpose.
What types of business funding are available?
Depending on the business and capital need, potential options may include working capital, term loans, business lines of credit, equipment financing, invoice financing, acquisition financing, refinancing, and other financing structures.
How much business funding should I apply for?
The amount should generally reflect the actual business need while remaining consistent with the company’s ability to support repayment and maintain healthy operating cash flow.
Does strong revenue guarantee business funding approval?
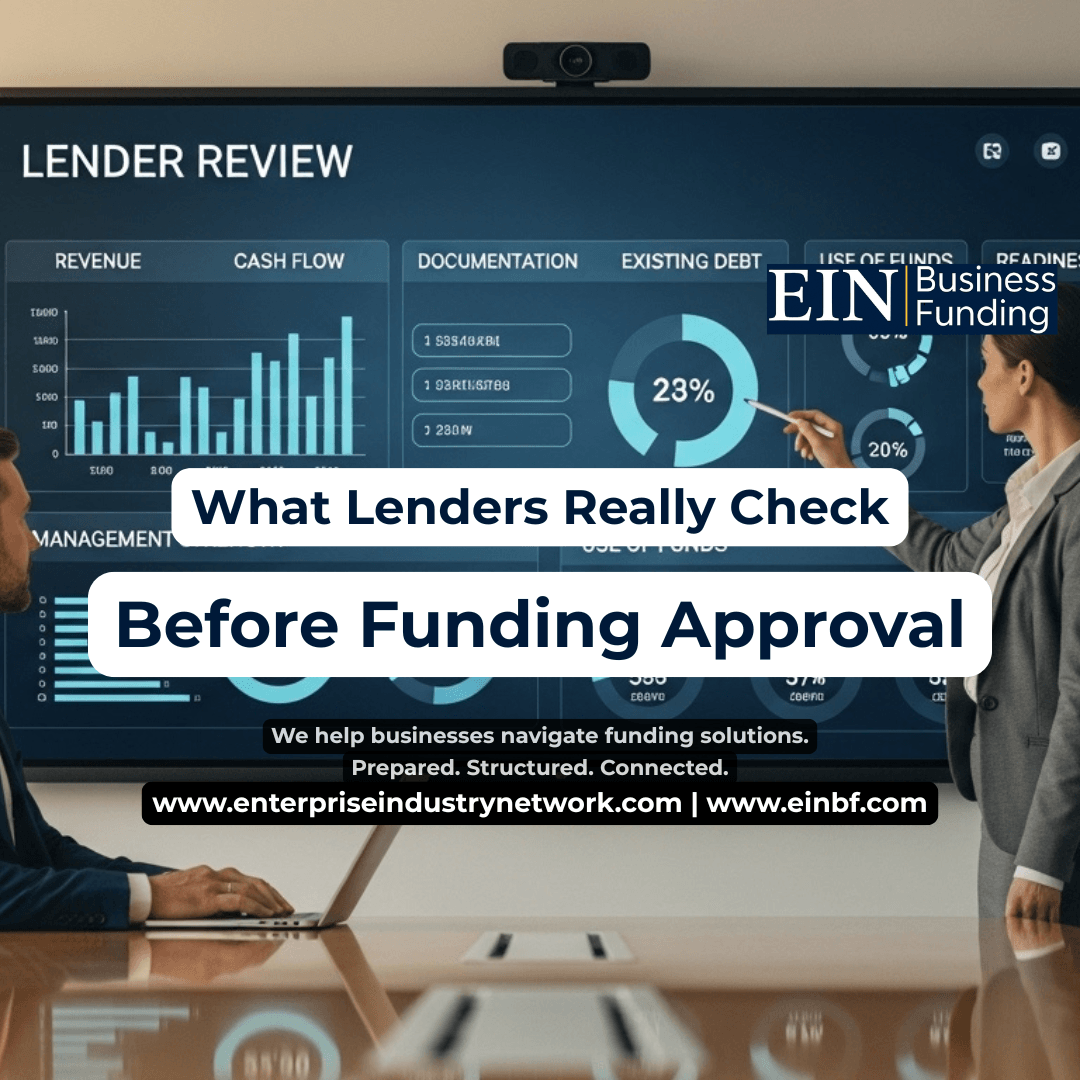
No. Funding providers may also evaluate cash flow, bank activity, repayment capacity, debt, credit profile, time in business, documentation, use of funds, and other underwriting factors.
When is the best time to prepare for business funding?
Ideally, preparation should begin before capital becomes urgent so the business has time to organize financial information, review funding needs, compare options, and address readiness issues.
 Before applying for business funding, owners should clarify the capital need, understand cash flow and existing obligations, organize financial records, and compare financing structures based on total cost and business fit.