Cash Flow vs Revenue: Why Lenders Look Beyond Sales Before Approving Business Funding
Why can a business generate strong revenue and still struggle to qualify for funding? Revenue shows how much money a company brings in, but lenders and funding providers often need to understand something deeper: how much cash actually remains available after operating expenses, debt obligations, payroll, inventory, taxes, and other business costs.
That is why cash flow can matter as much as—or sometimes more than—top-line revenue when evaluating business funding readiness. A company may report impressive sales while still experiencing financial pressure because of thin margins, slow customer payments, high expenses, substantial debt, or irregular cash movement.
In this long-form educational video, EIN Business Funding (EINBF), part of Enterprise Industry Network (EIN), explains the difference between revenue and cash flow, why lenders may look beyond sales, and what business owners should understand before seeking working capital, a business loan, line of credit, equipment financing, acquisition financing, or other business funding.
What Is the Difference Between Revenue and Cash Flow?
Revenue is the total income generated by a business from selling products or services before expenses are deducted.
Cash flow reflects the actual movement of money into and out of the company.
A business can therefore have strong revenue but weak cash flow if too much money is being absorbed by:
- Payroll.
- Rent and utilities.
- Inventory.
- Supplier payments.
- Taxes.
- Equipment expenses.
- Debt payments.
- Slow-paying customers.
- Low profit margins.
For funding purposes, this distinction matters because revenue does not automatically show whether the business has enough available cash to support new financing obligations.
Why Lenders Look Beyond Revenue
Revenue can help demonstrate that a business has customers and generates economic activity, but lenders may also want to know whether that revenue translates into sufficient cash to support repayment.
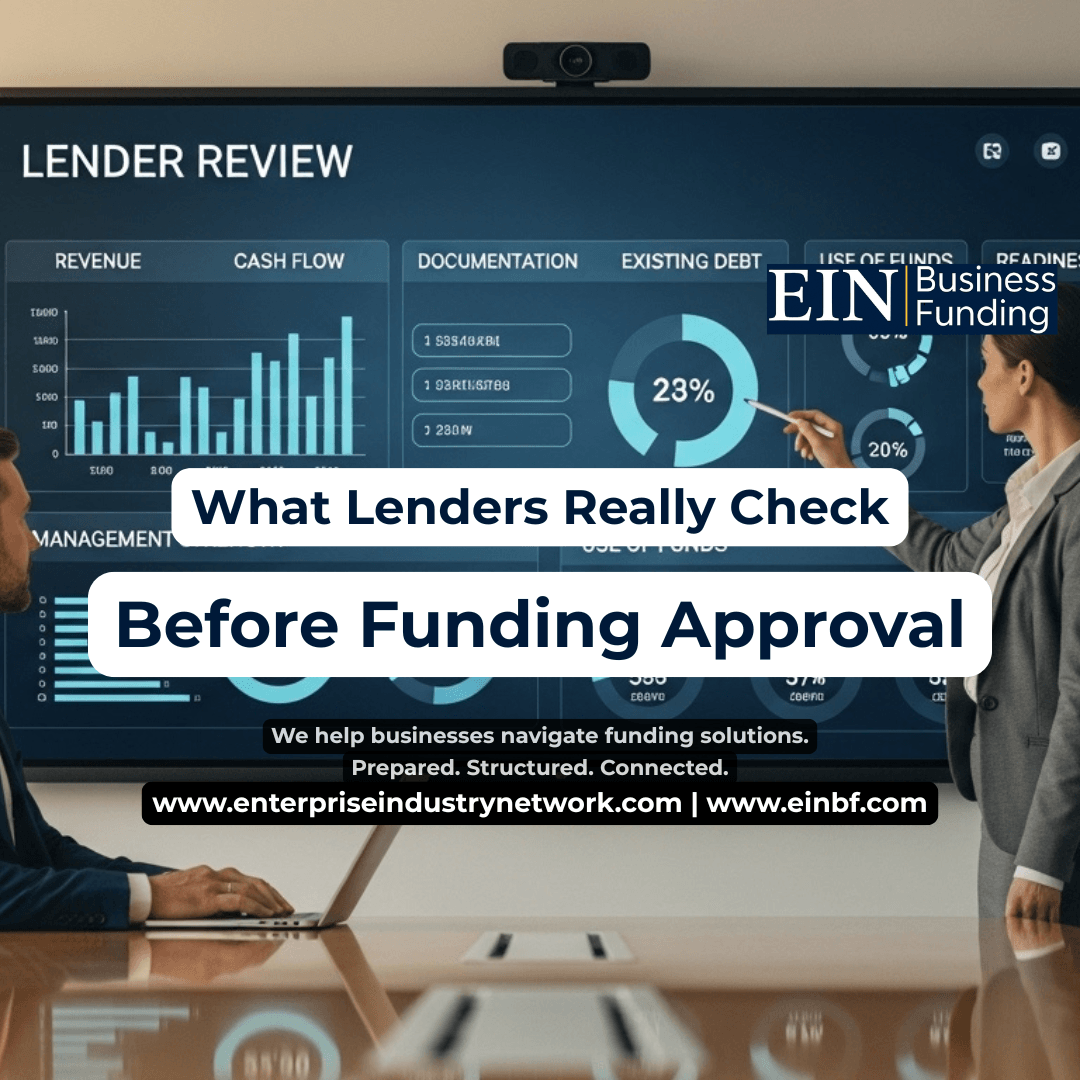
Depending on the financing product and provider, a funding review may consider:
- Business revenue.
- Revenue consistency.
- Operating cash flow.
- Profit margins.
- Business bank activity.
- Existing debt.
- Monthly financial obligations.
- Customer-payment patterns.
- Time in business.
- Credit profile.
- Requested funding amount.
- Intended use of funds.
The objective is not simply to determine whether the company sells enough. It is to understand whether the business appears capable of supporting the proposed financing.
Strong Revenue Does Not Always Mean Strong Cash Flow
Consider a business that generates significant monthly sales but operates with high expenses and narrow margins.
Another company may report substantial revenue but wait 60 or 90 days for customers to pay invoices while payroll, vendors, and operating costs must be paid immediately.
A third business may have healthy sales but also carry several loans, leases, or other recurring obligations.
All three companies may look strong when measured only by revenue, but their available cash could tell a very different story.
Why Cash Flow Matters for Repayment Capacity
Funding creates a financial obligation. Whether the structure is a term loan, line of credit, equipment financing arrangement, acquisition loan, or another type of capital, the business generally needs enough cash flow to support repayment.
Funding providers may therefore evaluate whether the company appears capable of paying:
- Normal operating expenses.
- Existing business debt.
- Taxes and payroll.
- Supplier obligations.
- New financing payments.
If cash flow is already under significant pressure, adding more debt may increase financial risk even when revenue appears strong.
How Business Bank Activity Can Reveal Cash Flow
Business bank statements can help show how money actually moves through the company.
Depending on the funding provider, bank activity may be reviewed for:
- Deposit consistency.
- Average balances.
- Recurring withdrawals.
- Existing loan payments.
- Overdraft activity.
- Seasonal changes.
- Large or unusual transactions.
Bank activity does not provide the entire financial picture, but it can help show whether actual cash movement supports the revenue reported by the business.
Profitability and Cash Flow Are Also Different
Profit and cash flow are related, but they are not identical.
A business can show accounting profit while still experiencing a shortage of cash. This can happen when revenue has been recorded but customers have not yet paid, when significant inventory has been purchased, or when large debt payments are due.
For funding readiness, owners should understand both profitability and actual liquidity.
Accounts Receivable Can Create Cash-Flow Pressure
Businesses that invoice customers may face a timing gap between completing work and receiving payment.
For example, a company may recognize revenue immediately but wait 30, 60, or 90 days for customers to pay.
During that period, the business may still need to cover:
- Payroll.
- Vendor payments.
- Inventory.
- Rent.
- Insurance.
- Debt payments.
- Other operating expenses.
This is one reason revenue alone may not reflect the company’s short-term funding position.
Margins Matter When Evaluating Revenue
Two companies can generate the same amount of revenue but have very different financial strength.
A company with healthy margins may retain more cash from each dollar of revenue. Another company with high operating costs may retain far less.
Business owners should therefore understand:
- Gross margin.
- Operating expenses.
- Net profitability.
- Debt-service requirements.
- Available cash after obligations.
The quality of revenue can matter as much as the total amount of revenue.
Existing Debt Can Reduce Available Cash Flow
Even a profitable business can become financially constrained when existing repayment obligations consume too much monthly cash.
Before seeking additional funding, owners should review:
- Outstanding loan balances.
- Business lines of credit.
- Equipment payments.
- Lease obligations.
- Merchant financing.
- Other recurring financial commitments.
Understanding these obligations can help determine whether additional financing is sustainable.
Seasonality Can Affect Funding Readiness
Some businesses generate revenue unevenly throughout the year.
A seasonal company may produce strong annual revenue but experience several months of lower cash flow.
Funding providers may therefore look at revenue and cash-flow patterns over time rather than relying on one particularly strong month.
Business owners should understand their seasonal operating cycle before choosing a financing structure and repayment schedule.
How Cash Flow Affects Working Capital Funding
Working capital financing is often used to help manage short-term operating needs such as payroll, inventory, supplier payments, seasonal expenses, or temporary cash-flow gaps.
When considering working capital, owners should understand whether the financing is supporting a temporary timing issue or covering a persistent operating shortfall.
Funding that addresses a temporary gap can be very different from repeatedly borrowing because the business does not generate enough cash to support normal operations.
How Cash Flow Affects a Business Line of Credit
A business line of credit can provide flexible access to capital for recurring or temporary needs.
However, if the company continually uses the full line and cannot meaningfully reduce the balance, that may indicate that the business is relying on borrowed capital to fund ongoing operations.
Owners should have a clear repayment plan and understand when expected cash inflows will allow the balance to be reduced.
How Cash Flow Affects Equipment Financing
Equipment financing may help preserve working capital by allowing a business to spread the cost of machinery, vehicles, technology, or other productive assets over time.
But the equipment should ideally generate enough operational value, efficiency, or revenue to justify the added repayment obligation.
The business should remain capable of meeting normal operating costs while also supporting the equipment payment.
How Cash Flow Affects Acquisition Financing
When buying an existing business, lenders may focus heavily on whether the acquired company can support the proposed financing after closing.
That review may include:
- Historical cash flow.
- Normalized earnings.
- Existing debt.
- Buyer contribution.
- Seller financing.
- Purchase price.
- Post-closing working-capital needs.
A business acquisition can have strong revenue and still be difficult to finance if the underlying cash flow cannot support the debt structure.
How Business Owners Can Improve Cash-Flow Visibility
Before seeking financing, owners can strengthen their understanding of cash flow by reviewing:
- Recent business bank statements.
- Monthly cash inflows.
- Monthly cash outflows.
- Accounts receivable.
- Accounts payable.
- Recurring debt payments.
- Seasonal changes.
- Operating expenses.
- Expected future obligations.
Better cash-flow visibility can help owners evaluate how much financing the business can realistically support.
Questions to Ask Before Seeking Business Funding
- How much revenue does the business generate?
- How much cash remains after operating expenses?
- Are customers paying on time?
- How much existing debt does the business carry?
- What are the monthly repayment obligations?
- Is cash flow stable or highly seasonal?
- How much additional financing can the business support?
- What will the funding be used for?
- Will the capital improve revenue, cash flow, efficiency, or business stability?
Revenue Opens the Conversation—Cash Flow Shows Capacity
Strong revenue can be an important positive indicator, but it should not be viewed in isolation.
Lenders and funding providers may look at whether the company can convert revenue into sufficient cash to support operations and new obligations consistently.
For business owners, understanding that distinction can improve funding readiness and help prevent taking on capital that the company may struggle to support.
Explore Business Funding with EIN Business Funding
EIN Business Funding (EINBF), part of Enterprise Industry Network, helps business owners approach financing with greater clarity by focusing on the financial position of the business, funding purpose, revenue, cash flow, existing obligations, timing, and the type of capital that may fit the need.
Depending on the business profile and funding purpose, potential financing options may include working capital, business loans, lines of credit, equipment financing, acquisition financing, invoice financing, refinancing, and other qualified business funding solutions.
Understand Your Cash Flow Before You Apply
Strong sales are only part of funding readiness. Review your cash flow, existing obligations, funding purpose, and repayment capacity before choosing a financing path.
Frequently Asked Questions
Why do lenders care about cash flow more than revenue?
Revenue shows how much the business generates, while cash flow can help show whether enough money remains after expenses and existing obligations to support additional financing payments.
Can a business have high revenue and poor cash flow?
Yes. High operating expenses, thin margins, slow customer payments, inventory requirements, seasonal fluctuations, and existing debt can all create cash-flow pressure even when revenue is strong.
Does strong revenue guarantee business funding approval?
No. Funding providers may also evaluate cash flow, bank activity, margins, existing debt, repayment capacity, credit profile, time in business, documentation, funding purpose, and other underwriting factors.
How can I improve business cash flow before applying for funding?
Owners can review receivables, operating expenses, debt payments, bank activity, inventory requirements, customer-payment timing, and other cash-flow drivers before taking on additional financing.
What financial information may lenders review?
Depending on the provider, lenders may review business bank statements, revenue trends, financial statements, cash flow, debt, margins, tax records, receivables, credit information, and the intended use of funds.
Why is cash flow important for acquisition financing?
The acquired business generally needs enough cash flow to support operations, existing obligations, acquisition debt payments, and post-closing working-capital needs.
 Strong revenue can start a funding conversation, but lenders may look deeper at cash flow, operating expenses, existing debt, margins, and repayment capacity before approving business financing.