Invoice Financing With EIN: Can Net-30, Net-60 or Net-90 B2B Invoices Unlock Working Capital?
A profitable B2B company can still run short of cash when customers pay on Net-30, Net-60 or Net-90 terms. The business has already completed the work or delivered the product, but the cash remains locked in accounts receivable.
Invoice financing is designed around that timing problem. Instead of waiting for the full customer-payment period, an eligible business may be able to use qualified unpaid invoices as part of a working-capital financing structure.
When Does Invoice Financing Become Relevant?
Invoice financing generally becomes relevant after the business has delivered the product or completed the service and issued an eligible invoice to a commercial customer.
If the company has not yet fulfilled the order, purchase order financing or another working-capital structure may be more relevant.
Does an EIN Alone Qualify the Business?
No. An EIN identifies the company, but invoice financing with an EIN does not mean the tax ID alone determines eligibility.
The provider may evaluate the invoice, customer, business, receivable quality and other transaction-specific factors.
Why Customer Quality Matters
In receivables-based financing, the ability of the commercial customer to pay can matter significantly.
An invoice owed by an established business with reliable payment history may be viewed differently from an invoice owed by a financially weak customer or one already substantially overdue.
Net-30, Net-60 and Net-90 Create Different Cash Gaps
A business paid in 30 days may be able to carry the gap from existing cash. A company routinely waiting 60 or 90 days may need more working capital to continue paying payroll, suppliers and operating expenses.
The longer the payment cycle, the more cash can become trapped in receivables as the business grows.
Growth Can Make the Problem Bigger
More sales do not always improve immediate liquidity.
A business that doubles its B2B sales while continuing to offer Net-60 terms may also double the amount of money temporarily tied up in outstanding invoices.
That is why fast-growing B2B businesses can experience cash pressure even while reporting higher revenue.
What Is an Accounts Receivable Aging?
An accounts receivable aging organizes unpaid invoices according to how long they have been outstanding.
It can show which invoices are current and which are becoming overdue.
For financing purposes, a current invoice from a qualified customer can present differently from an invoice that is already far beyond its payment terms.
What Should Be Prepared?
- Eligible B2B invoices
- Customer names and payment terms through the secure process
- Accounts receivable aging
- Invoice amounts
- Invoice dates
- Expected customer payment dates
- Annual business revenue
- Existing business debt
- Exact working-capital requirement
How Is Invoice Financing Different From a Business Line of Credit?
A line of credit is a broader revolving financing facility based primarily on the business and borrower profile.
Invoice financing is tied more directly to eligible receivables.
A company with recurring B2B invoices may compare both structures depending on credit, business history, revenue, receivables quality and ongoing capital needs.
How Is It Different From a Working Capital Loan?
A working-capital loan may be based more broadly on the business’s revenue, credit and cash flow.
Invoice financing focuses on money the business has already earned but has not yet collected.
The best fit depends on why cash is tight.
What if Some Customers Pay Quickly and Others Pay Slowly?
Do not treat every receivable the same.
Review which customers create the largest cash gaps and which invoices are most significant to working capital.
The business may not need to finance every outstanding invoice.
Should Consumer Invoices Be Treated the Same Way?
Invoice financing is commonly associated with business-to-business receivables rather than ordinary consumer receivables.
Eligibility depends on the provider and the specific receivable structure.
Existing Debt Still Matters
Even when the financing is receivables-driven, the business should prepare its current loans, lines of credit and other obligations.
The provider needs an accurate picture of the company’s financial position and any existing claims or financing arrangements that may affect receivables.
Invoice Financing Should Solve the Collection Timing Gap
The goal is not simply to borrow because invoices exist.
The business should understand how much cash is tied up in receivables, what operating expenses must be paid before customers pay and how frequently the timing problem occurs.
If your company has completed B2B work, issued invoices and is now waiting 30 to 90 days for customer payment, complete the EIN Business Funding Quick Lead Pre-Qualification using your current revenue, receivables and funding requirement.
FAQs
Can an unpaid B2B invoice potentially be used for financing?
Potentially. Eligibility depends on the invoice, customer, provider and complete transaction.
Does invoice financing with an EIN mean EIN-only approval?
No. An EIN identifies the business, while the provider may also evaluate the receivable, customer and other business information.
Is invoice financing the same as a business line of credit?
No. Invoice financing is tied more directly to eligible receivables, while a line of credit is generally a broader revolving business-financing structure.
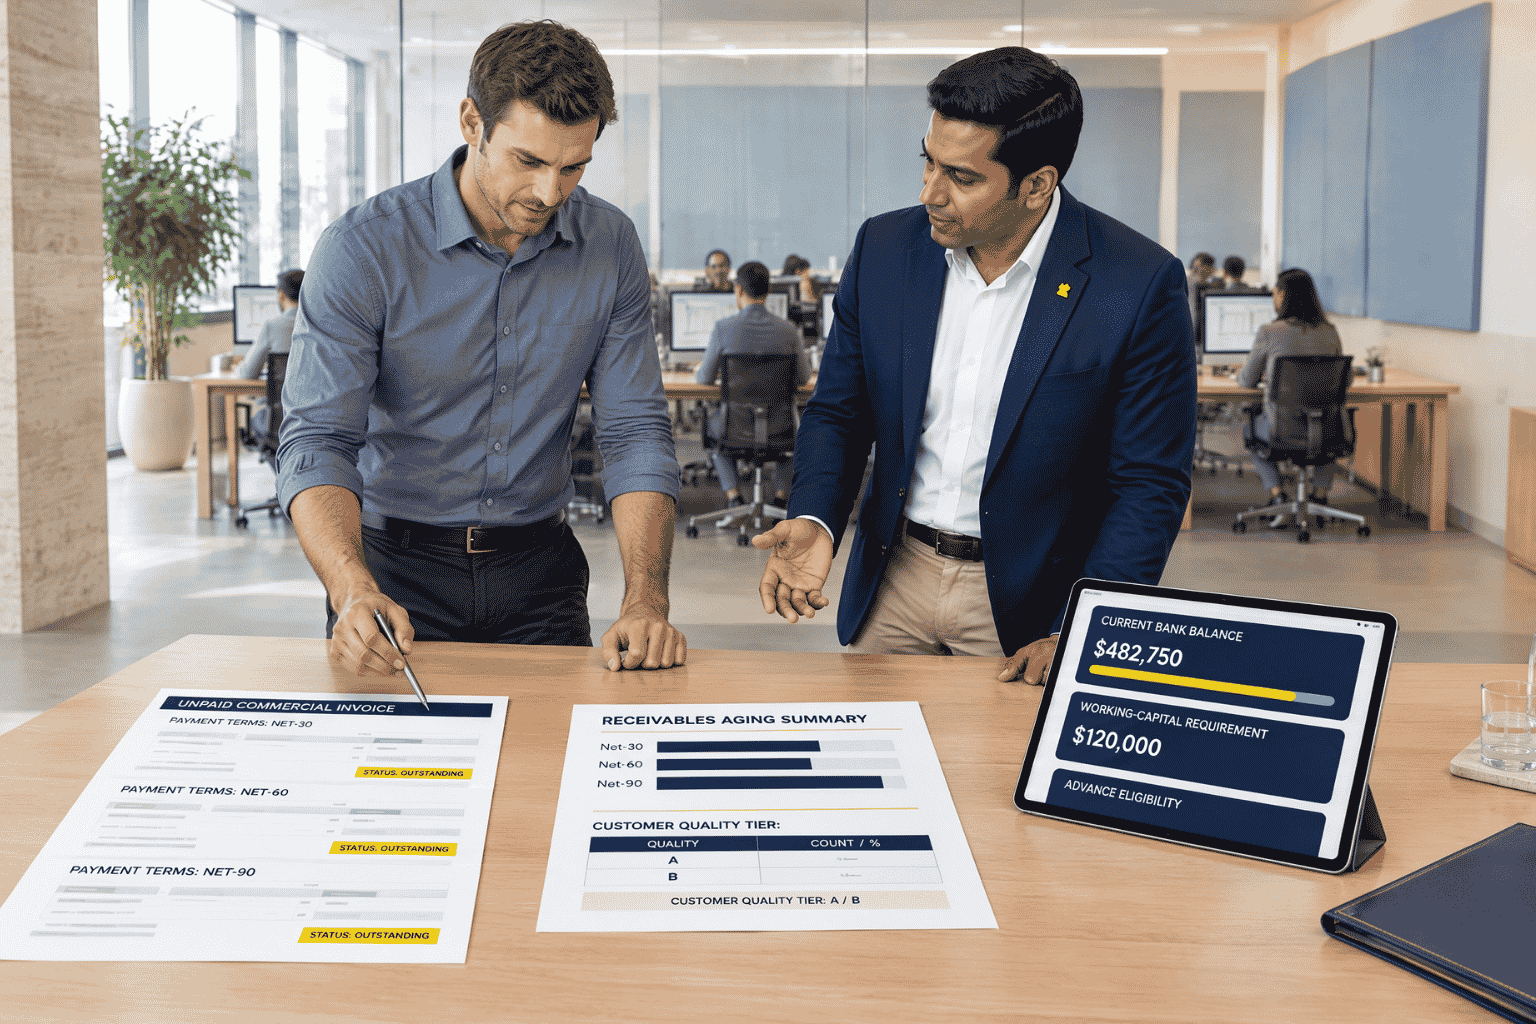 B2B businesses can face a working-capital gap when completed work is tied up in Net-30, Net-60 or Net-90 receivables.